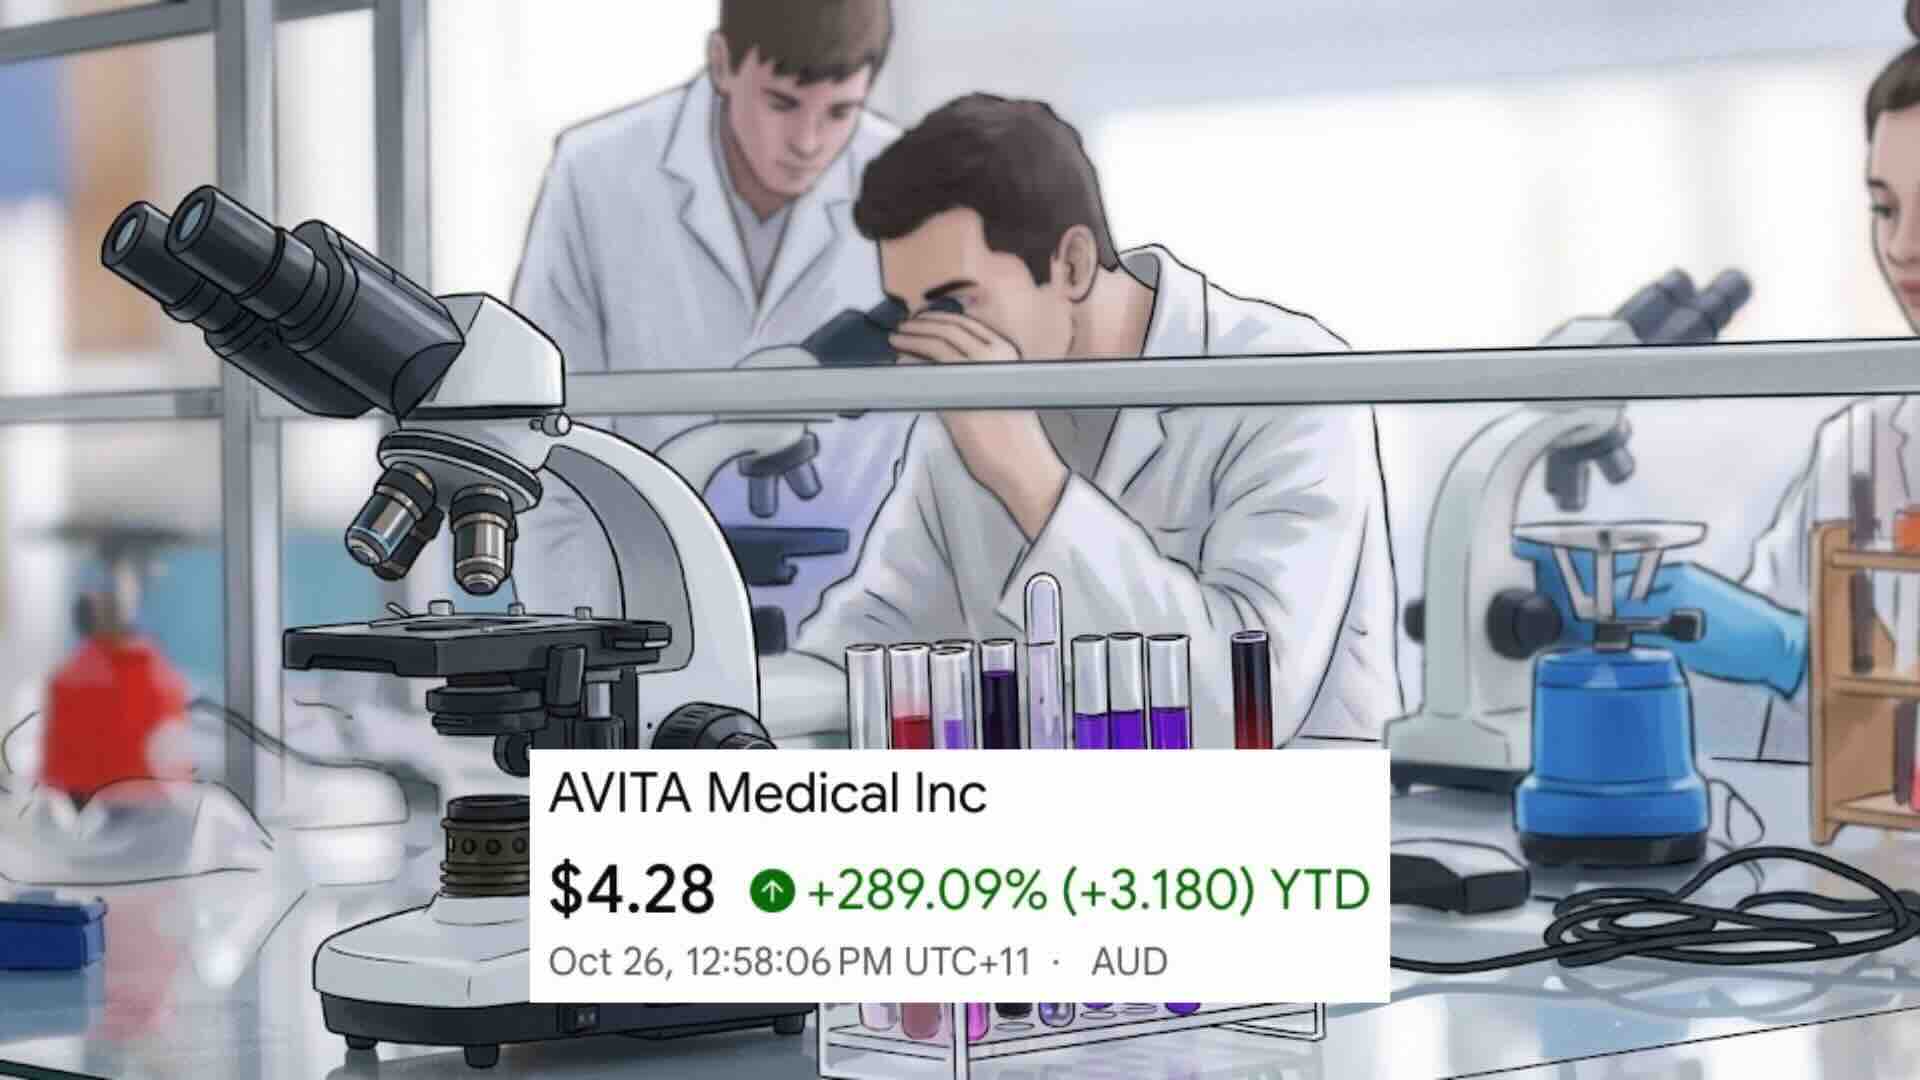
AVITA Medical (ASX: AVH) shares have gained approximately 290% year-to-date, reflecting renewed investor interest in its specialised wound care technology. We see a potentially interesting opportunity in a company seeking to improve how severe burns and complex wounds are treated, with its next challenge being to turn growing product adoption into sustainable cash generation.
The numbers behind the opportunity
- Q2 revenue: US$21.7 million, up 18% year-on-year.
- Gross margin: 81.9%.
- 2026 revenue guidance: US$86 million to US$89 million.
- Quarter-end cash: US$11.1 million.
- Target: Cash flow break-even in Q4 2026.
More than a burns treatment
AVITA's flagship RECELL system uses a patient's own skin cells to create a spray-on treatment for burns and certain other wounds. The technology underpins an established commercial business, while Cohealyx and PermeaDerm offer opportunities to expand into broader wound management.
Recent developments suggest the portfolio is gaining traction. Second-quarter revenue reached a record US$21.7 million, supported by RECELL, while Cohealyx generated US$1.7 million and PermeaDerm contributed US$0.6 million. Positive PermeaDerm clinical study results announced in August also strengthened its potential as an alternative to allograft for temporarily protecting wounds.
Our interest lies in whether these newer products can expand AVITA's addressable market rather than simply supplement existing sales. If adoption grows, the company could develop a broader revenue base around its wound healing technology.
The opportunity comes with a catch
AVITA's cash use fell to approximately US$3.2 million in Q2 from US$9.9 million in Q1, and management lifted its full-year revenue outlook. These are encouraging signs that commercial growth and cost discipline are beginning to improve its financial position.
However, the company held just US$11.1 million in cash and marketable securities at quarter-end. Its fourth-quarter break-even target is therefore crucial, particularly after the substantial share-price rally.
Investor Insight: Can growth justify expectations?
We see a potentially compelling commercial story, but the opportunity depends on execution. RECELL provides an established revenue base, while Cohealyx and PermeaDerm could broaden future growth. The key evidence will be rising sales alongside declining cash consumption. Without that combination, the share-price gain may prove difficult to sustain.
The next milestone
AVITA's next quarterly results, scheduled for November 6, should help investors assess progress towards break-even. We will be looking for evidence that newer products are gaining commercial momentum and that cash consumption continues to fall. Can AVITA turn promising wound care technology into a consistently cash-generative business?


 Mark Elzayed•





