STOCKSCOPE

4DMedical (ASX: 4DX) Delivers 66% Revenue Growth, but Can Its 724-Site Network Justify a $2.2 Billion Valuation?

Danny Aad

Danny Aad

Technology & Biotechnology Specialist | StockScope

Published:28 Oct 2026
4DMedical (ASX: 4DX) Delivers 66% Revenue Growth, but Can Its 724-Site Network Justify a $2.2 Billion Valuation?

Record scan volumes, expanding hospital adoption and a 66% jump in quarterly revenue suggest 4DMedical Limited (ASX: 4DX) is gaining commercial traction in respiratory imaging. But with a market valuation exceeding $2 billion and substantial ongoing cash expenditure, the critical question is whether its growing global footprint can generate enough revenue to justify expectations.

The company's latest quarterly results highlight both the scale of its opportunity and the financial challenge ahead.

Key numbers

  • $2.3 million: Unaudited operating revenue for Q1 FY27, up 66% year-on-year.
  • 119,672 scans: Quarterly record, representing 61% annual growth.
  • 724 locations: Global software-as-a-service installation base at 30 September 2026.
  • $242.8 million: Cash balance at quarter-end, following operating outflows of $15.2 million.
  • Above 90%: Reported gross margins, supporting the potential scalability of its software business.

The latest development: Commercial adoption accelerates

4DMedical's September quarter demonstrated growing demand for its respiratory imaging technology across hospitals, radiology providers and healthcare networks.

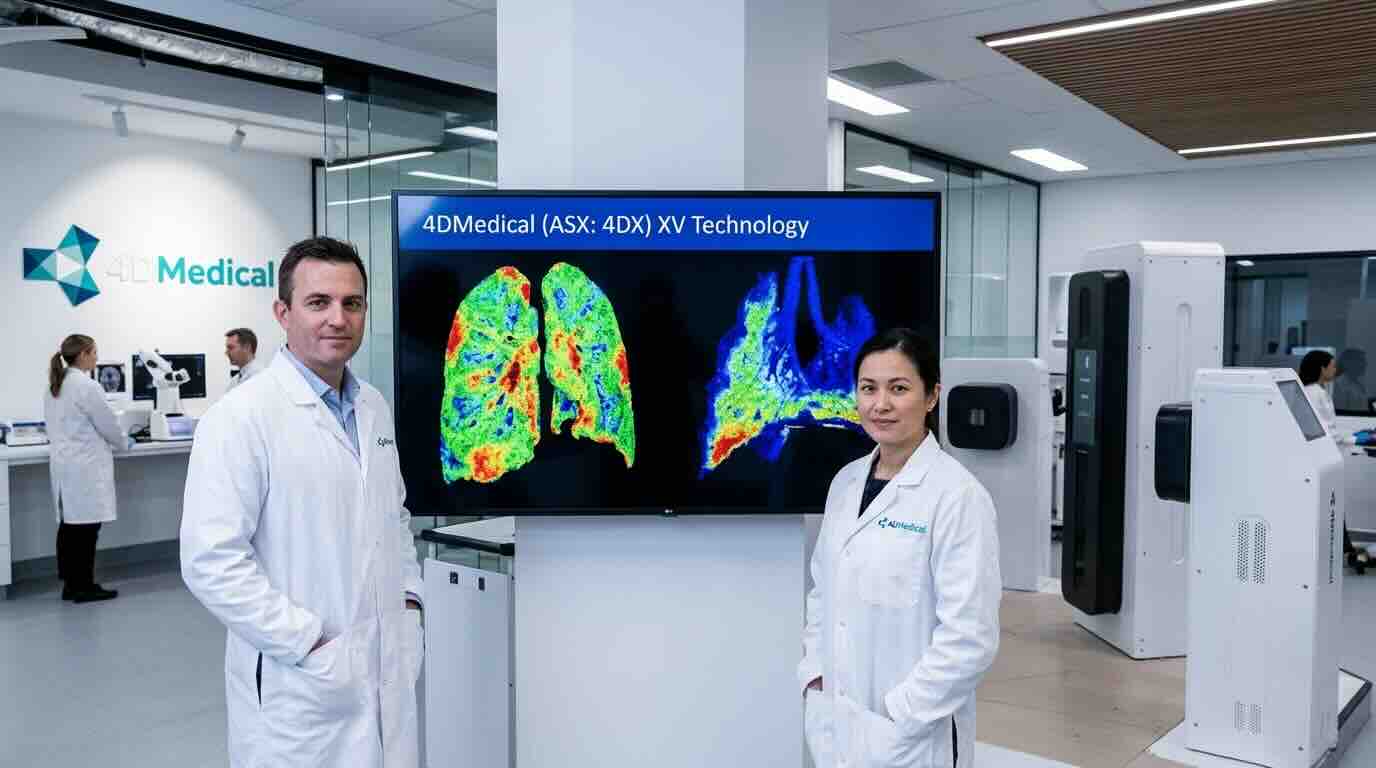
Its CT:VQ software enables detailed lung ventilation and perfusion analysis using existing CT imaging equipment without intravenous contrast agents.

The technology has secured regulatory approvals across major international markets, including the United States, Australia and Europe.

During the quarter, 4DMedical completed deployment of CT:VQ and LDAf software across SimonMed Imaging's 125 CT-enabled locations in the United States.

SimonMed also signed an additional three-year subscription agreement for IQ-UIP, expanding the commercial relationship beyond the original products.

Meanwhile, a US Veterans Affairs healthcare network selected 4DMedical's LDAi technology for chronic obstructive pulmonary disease detection.

The agreement carries an estimated value of US$800,000 over five years, although its initial one-year term means future revenue depends on extensions.

What stands out to us

We think 4DMedical's commercial opportunity is becoming more credible, particularly as its software gains acceptance within established healthcare networks.

Its proprietary imaging technology, clinical relationships and regulatory clearances provide potential competitive advantages.

However, the financial picture requires closer examination.

FY26 operating revenue reached $7.1 million, while adjusted net losses totalled approximately $32.9 million.

The latest quarter consumed $15.2 million in operating cash, alongside $22.5 million in investing outflows, primarily associated with acquisitions and strategic investments.

The substantial cash balance provides financial flexibility, but the company's valuation remains demanding.

At approximately $3.61 per share on 27 October, its market capitalisation was around $2.17 billion, equivalent to more than 300 times FY26 revenue.

That multiple places considerable weight on future commercial expansion rather than current earnings.

What the company is doing now

4DMedical is expanding its diagnostic portfolio through acquisitions, partnerships and international distribution agreements.

Its acquisition of Austrian medical imaging business contextflow established a European commercial platform, including a German lung cancer screening deployment covering approximately 25,000 procedures across three years.

The company is also advancing its CLEAR clinical program, which evaluates CT:VQ for suspected acute pulmonary embolism.

Results expected in 2027 could provide important evidence supporting wider clinical adoption.

Additional agreements with Australian imaging providers and the renewal of Stanford Medicine's software arrangements further strengthen its commercial reach.

Insight: Is 4DMedical's Growth Enough to Support Its Valuation?

We think 4DMedical possesses promising technology and increasingly credible commercial relationships, supported by regulatory approvals and high software gross margins. Its cash reserves substantially reduce immediate funding pressure, allowing management to pursue expansion without relying on near-term profitability.

However, the valuation already anticipates considerable future success. Revenue remains small relative to market capitalisation, while operating cash consumption is substantial.

Our assessment would strengthen if higher scan utilisation translated into accelerating recurring revenue, narrower operating losses and improving cash conversion without disproportionate additional expenditure.

What happens next?

The next quarterly results will test whether rapid network expansion produces sustained revenue growth rather than simply more installed locations.

Particular attention should fall on SimonMed utilisation, US healthcare contract renewals and progress towards the CLEAR clinical readout.

Management's reported cash balance represents approximately 16 quarters

Danny Aad

Danny Aad

(Technology & Biotechnology Specialist | StockScope)

Danny Aad is an experienced technology executive with a distinguished career spanning more than three decades, including senior leadership positions as Chief Technology Officer (CTO) across the technology and biotechnology sectors. With extensive expertise in technology strategy, digital innovation and the evolving biotechnology landscape, Danny brings a wealth of industry knowledge and technical insight to his analysis of emerging technologies, corporate developments and investment opportunities.

DisclaimerInformation on Stockscope is general in nature and does not constitute financial product advice. It does not take into account your personal objectives, financial situation or needs. Seek independent advice from a qualified financial adviser before making an investment decision. Stockscope and its affiliates do not guarantee the accuracy or completeness of information published on this website. To the extent permitted by law, they accept no liability for any claim, loss or damage arising from its use or reliance on it. Stockscope and its associates may have commercial relationships with companies featured on this website, hold securities in those companies, or receive commissions in connection with capital raisings.

Continue Reading

ASX Weathers Wall Street's AI Rout, but Three Market Risks Are Becoming Harder to Ignore
Market Briefings
Market Briefings

ASX Weathers Wall Street's AI Rout, but Three Market Risks Are Becoming Harder to Ignore

Australian equities: what moved the ASX 200? Australian shares finished lower on Friday, 6 November, as the technology-led sell-off on Wall Street spread across global markets. The ASX 200...

Mark ElzayedMark Elzayed•
Epiminder (ASX: EPI) Expands FDA Clearance as $65 Million Cash Reserve Faces a Crucial Commercial Test
Biotech & Health
Biotech & Health

Epiminder (ASX: EPI) Expands FDA Clearance as $65 Million Cash Reserve Faces a Crucial Commercial Test

Epiminder Limited ASX: EPI has expanded the US market for its epilepsy monitoring technology following a significant regulatory clearance, strengthening its commercial prospects ahead of a p...

Danny AadDanny Aad•
Asara Resources (ASX: AS1) Hits 38m at 2.1g/t Gold: Could Sogosogoba Unlock Kada's Next Growth Phase?
Mining
Mining

Asara Resources (ASX: AS1) Hits 38m at 2.1g/t Gold: Could Sogosogoba Unlock Kada's Next Growth Phase?

A 38-metre gold intersection grading 2.1 grams per tonne has given Asara Resources Limited ASX: AS1 an encouraging exploration result beyond its established Massan deposit in Guinea. The dis...

Alison ElzayedAlison Elzayed•
Alvo Minerals (ASX: ALV) Expands Rare Earth Discovery Across 6.5km², but Can It Deliver Economic Value?
Mining
Mining

Alvo Minerals (ASX: ALV) Expands Rare Earth Discovery Across 6.5km², but Can It Deliver Economic Value?

Alvo Minerals Limited ASX: ALV has extended rare earth mineralisation approximately 2 kilometres beyond previously tested areas at its Boa Vista prospect in Brazil, strengthening the explora...

Alison ElzayedAlison Elzayed•
Avenira Limited (ASX: AEV) Raises $48.9 Million as Wonarah Phosphate Project Faces Its Biggest Test Yet
Mining
Mining

Avenira Limited (ASX: AEV) Raises $48.9 Million as Wonarah Phosphate Project Faces Its Biggest Test Yet

Avenira Limited ASX: AEV has reached a significant financing milestone, with its $48.9 million rights issue providing fresh capital to advance the Wonarah Phosphate Project in the Northern T...

Alison ElzayedAlison Elzayed•
Mayne Pharma Group (ASX: MYX) Unveils $55.5 Million Sale, but Can Its US Business Deliver Stronger Profits?
Biotech & Health
Biotech & Health

Mayne Pharma Group (ASX: MYX) Unveils $55.5 Million Sale, but Can Its US Business Deliver Stronger Profits?

Mayne Pharma Group Limited ASX: MYX is taking a decisive step towards becoming a US-focused pharmaceutical company, agreeing to sell its international operations for $55.5 million. The tran...

Danny AadDanny Aad•
Loading more stories...







