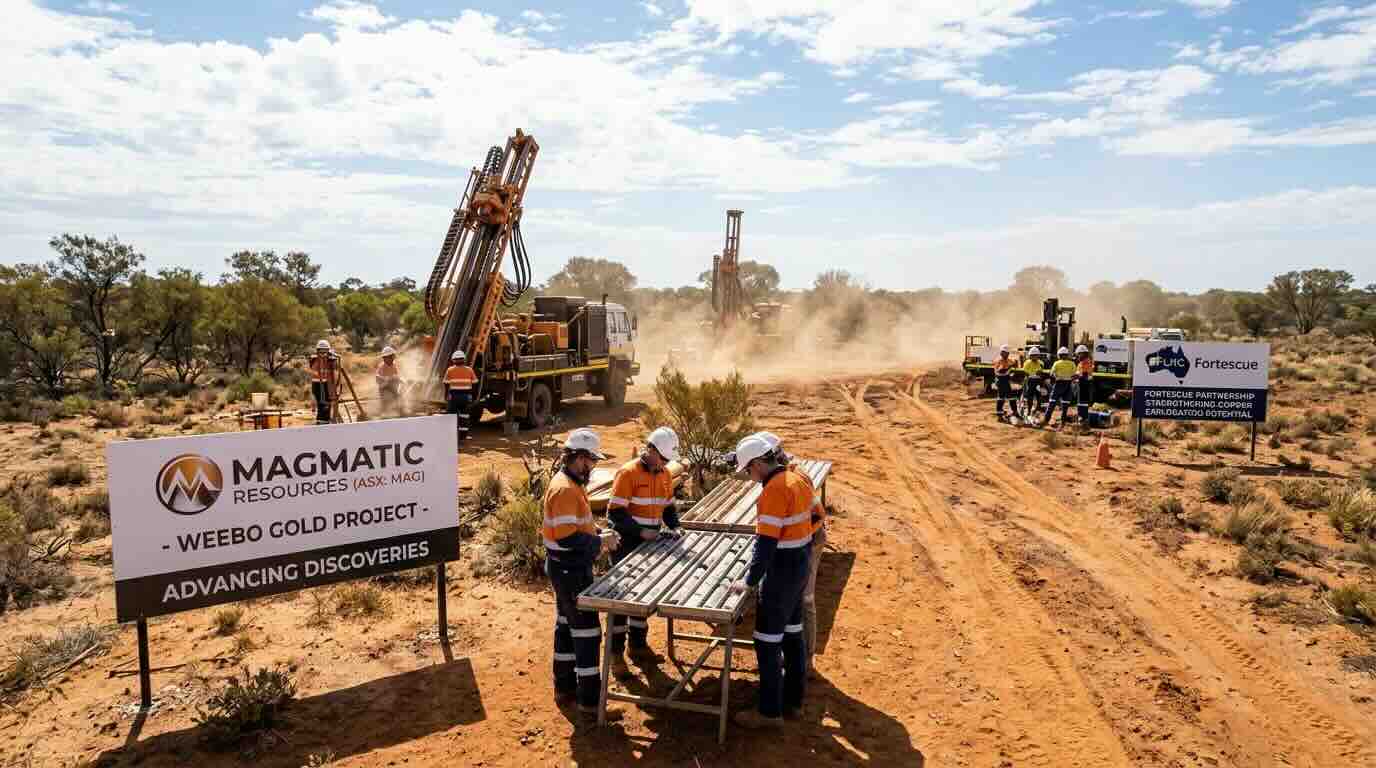
Magmatic Resources (ASX: MAG) is advancing a dual-commodity exploration strategy following encouraging gold drilling results at its Weebo Project in Western Australia and continued copper-gold exploration at Myall in New South Wales.
The company's September 2026 drilling campaign has strengthened its search for a substantial gold discovery, while its partnership with Fortescue provides externally funded exposure to large-scale copper exploration.
The central question is whether these programmes can establish economically significant mineral resources without placing excessive pressure on Magmatic's finances.
Key numbers
- 270 square kilometres: Approximate area of the Weebo Gold Project in Western Australia's Yandal Greenstone Belt.
- 6,591 metres: Phase 3 drilling completed at Weebo during May and June 2026.
- 6m at 3.4g/t gold: Significant drilling intersection at the Scone Stone prospect.
- $3.9 million: Expanded FY2026 exploration budget for the Fortescue-supported Myall Project.
- $5.54 million: Cash reserves at 30 June 2026, alongside a $4.48 million annual net loss.
Weebo drilling brings Magmatic closer to defining a gold discovery
Magmatic's latest exploration activities have concentrated on identifying continuous gold-bearing structures across the Weebo Project.
On 25 September 2026, the company confirmed completion of follow-up reverse circulation drilling designed to investigate mineralisation identified during earlier campaigns.
The programme followed encouraging July results from several prospects, including Otto 2, Ockerburry 3 and Scone Stone.
At Otto 2, drilling returned 6m grading 1.96 grams per tonne gold, including 4m at 2.74g/t.
Ockerburry 3 delivered 8m at 1.52g/t gold, while Scone Stone produced 6m at 3.4g/t, including 1m at 13.9g/t.
These intersections demonstrate gold mineralisation across multiple targets, strengthening the geological rationale for additional drilling.
Importantly, aircore drilling also identified gold-bearing structures extending more than 700m at regional prospects.
However, individual intersections do not establish a commercially viable deposit.
Magmatic must demonstrate sufficient mineralisation continuity, thickness and grade before meaningful resource estimates or mine development economics can emerge.
Fortescue partnership provides a different route to growth
While Weebo represents Magmatic's principal gold exploration opportunity, Myall offers exposure to copper-gold discoveries in New South Wales' prospective East Lachlan region.
The project is being explored under a farm-in and joint venture agreement with Fortescue subsidiary FMG Resources.
Under the agreement, Fortescue can earn up to 75% ownership through exploration expenditure totalling $14 million, subject to the agreement's conditions.
This arrangement provides Magmatic with access to substantial exploration funding while limiting its direct financial exposure.
During FY2026, Myall's exploration budget increased from approximately $3.5 million to $3.9 million.
The programme included 16 diamond drill holes totalling 6,240.4m, targeting prospects including Interceptor, Barina and Calais.
Exploration has identified copper-gold mineralisation, although results remain preliminary.
The commercial attraction lies in potentially discovering a substantial porphyry system within an established mineral district.
Nevertheless, Fortescue's expenditure commitments do not constitute revenue from mining operations or guarantee a discovery.
Cash reserves improve, but exploration expenditure remains substantial
Magmatic's FY2026 results highlight the financial realities of advancing multiple exploration projects.
The company reported a net loss of $4.48 million, compared with approximately $2.17 million in FY2025.
Cash reserves increased to $5.54 million from $4.74 million, supported by additional equity funding.
Although this provides flexibility for ongoing drilling, the widening accounting loss demonstrates the cost of maintaining an active exploration portfolio.
Magmatic does not yet generate meaningful revenue from mineral production.
Consequently, earnings-based valuation multiples are unsuitable.
A more appropriate assessment depends on discovery potential, exploration expenditure, available funding and the probability of establishing economically recoverable resources.
Future capital raisings could dilute shareholders if exploration expenditure exceeds available cash.
What could establish Magmatic's next growth opportunity?
Magmatic's next important milestones involve assay results from September's Weebo drilling and additional exploration outcomes from Myall.
At Weebo, evidence of continuous, higher-grade mineralisation would strengthen the potential for resource-definition drilling.
At Myall, further copper-gold intersections could justify expanded exploration expenditure under the Fortescue partnership.
Both projects remain exposed to geological uncertainty, while future development would require substantial technical studies and funding.
Insight: Fortescue funding could make Magmatic's gold exploration more sustainable
What stands out to us is Magmatic's ability to pursue two exploration opportunities with different funding structures. Its $5.54 million cash balance supports company-funded drilling at Weebo, while Fortescue's potential $14 million expenditure commitment provides exposure to Myall without requiring Magmatic to fund the entire programme. This distinction could improve capital efficiency, although discovery risk remains considerable. We see the strongest opportunity in demonstrating economically meaningful mineralisation at Weebo, with the next decisive test being consistent gold grades and mineralised widths across follow-up drilling.

 Mark Elzayed•






