Alara Resources (ASX: AUQ) has delivered a significant financial turnaround, reporting a $19.7 million annual net profit as its Al Wash-hi Majaza copper operation in Oman continues producing above designed capacity.
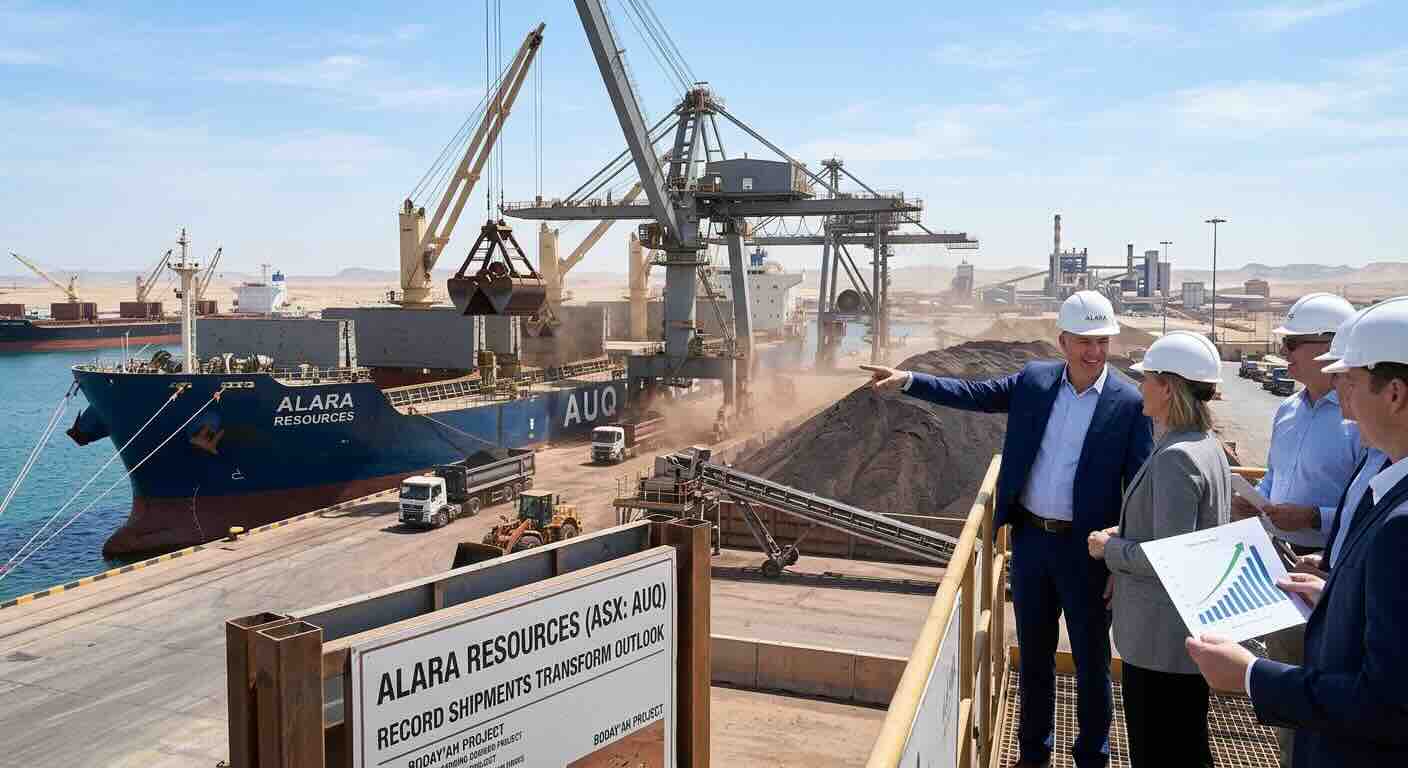
The company's 27 October 2026 quarterly update revealed record concentrate shipments, strong operating cash generation and further exploration progress.
With production accelerating and cash reserves strengthening, the central question is whether Alara can sustain profitability while managing rising mining costs and expanding its mineral resource base.
Key numbers
- $134.4 million: FY2026 copper sales revenue, compared with $55.1 million in FY2025.
- $19.7 million: FY2026 net profit, reversing the previous year's $19 million loss.
- 15,199 tonnes: Copper concentrate dispatched during the September 2026 quarter.
- $24.74 million: Net operating cash inflow during the September quarter.
- $42.28 million: Group cash reserves at 30 September 2026.
Record copper shipments demonstrate stronger operations
Alara's September quarter marked another operational milestone at its 51%-owned Al Wash-hi Majaza copper-gold project.
The operation processed 285,141 tonnes of ore, exceeding its quarterly processing target of 249,000 tonnes by approximately 14%.
Copper concentrate production reached 11,028 wet metric tonnes, while the company dispatched 15 shipments containing approximately 15,199 tonnes of concentrate.
Those shipments contained an estimated 2,952 tonnes of copper and 1,247 ounces of gold.
The discrepancy between concentrate produced and shipped reflects inventory movements, highlighting why production and sales volumes must be assessed separately.
Importantly, these results were achieved despite regional shipping disruptions, container shortages and congestion at Sohar Port.
Maintaining above-nameplate processing performance suggests that earlier commissioning challenges have been substantially reduced.
However, operational efficiency must remain consistent as mining progresses into different ore zones.
Profitability signals a major change in financial performance
Alara's FY2026 results demonstrate how higher production volumes have transformed its financial position.
Copper sales revenue increased approximately 144%, from $55.1 million to $134.4 million.
The company moved from a $19 million net loss in FY2025 to a $19.7 million profit in FY2026.
This turnaround reflects the growing contribution from commercial production at Al Wash-hi Majaza.
However, consolidated profitability should not be confused with earnings entirely attributable to Alara shareholders.
Approximately $11.3 million of FY2026 profit was attributable to Alara's owners, with the remainder attributable to non-controlling interests.
The distinction matters because the company owns 51% of the operating project.
The latest quarterly cash flow figures are particularly encouraging.
Customer receipts reached $60.04 million, while operating activities generated $24.74 million in net cash.
After investing outflows of $4.34 million and financing outflows of $5.23 million, group cash reserves increased to $42.28 million.
These figures suggest stronger financial flexibility, although they do not establish that the quarterly cash generation rate will continue indefinitely.
Mining costs and logistics remain important risks
Al Wash-hi Majaza mined approximately 333,647 tonnes of run-of-mine ore during the September quarter.
Waste movement reached 2.12 million tonnes, producing a strip ratio of 6.35 tonnes of waste for each tonne of ore.
That ratio deserves attention because higher waste removal can increase mining expenditure and affect margins.
The reported copper grade of 0.88% also highlights the importance of maintaining throughput and metallurgical recoveries.
Meanwhile, ongoing shipping disruptions could affect concentrate deliveries, working capital and revenue recognition.
An appeal relating to previously dismissed legal claims against the project is scheduled for November 2026, creating another uncertainty.
Exploration could extend the operating opportunity
Beyond established production, Alara is advancing exploration across Oman's Block 22B concession.
The company completed a 6,132-line-kilometre airborne electromagnetic and magnetic survey covering approximately 1,448 square kilometres.
Exploration identified 12 copper-gold prospect areas, including five priority targets requiring further investigation.
Successful discoveries could potentially extend production life or support additional processing capacity.
However, exploration targets remain speculative until drilling establishes economically meaningful mineralisation.
Insight: Cash generation may be Alara's most important competitive advantage
What stands out to us is the relationship between Alara's improving production performance and its strengthened financial position. The September quarter's $24.74 million operating cash inflow provides an opportunity to fund exploration, manage debt and improve operational resilience. However, sustaining this performance depends on copper grades, mining costs and reliable concentrate shipments. We believe the market should focus less on headline production records and more on whether operating margins remain resilient. The decisive next measure will be quarterly cash generation relative to waste movement and concentrate sales.

 Mark Elzayed•






