Delorean Corporation is approaching a significant transition, with its flagship Salisbury bioenergy facility receiving its operational licence in October 2026 and construction reaching approximately 90% completion. The milestone brings the company closer to generating renewable gas revenues under an established long-term agreement with Origin Energy. With a second major project progressing towards financing, Delorean is beginning to demonstrate how its engineering expertise could translate into a portfolio of recurring renewable energy infrastructure earnings.
Key numbers
- $9.34 million: FY2026 revenue, with EBITDA improving to $985,000.
- Up to $55 million: Contracted revenue opportunities associated with SA1's biomethane and liquid carbon dioxide offtake arrangements.
- 210 terajoules: Target annual biomethane production capacity at SA1.
- $30.5 million: Government grants secured for the NSW1 Horsley Park development.
- $200 million+: Near-term renewable gas infrastructure development pipeline.
Salisbury moves closer to its first commercial production
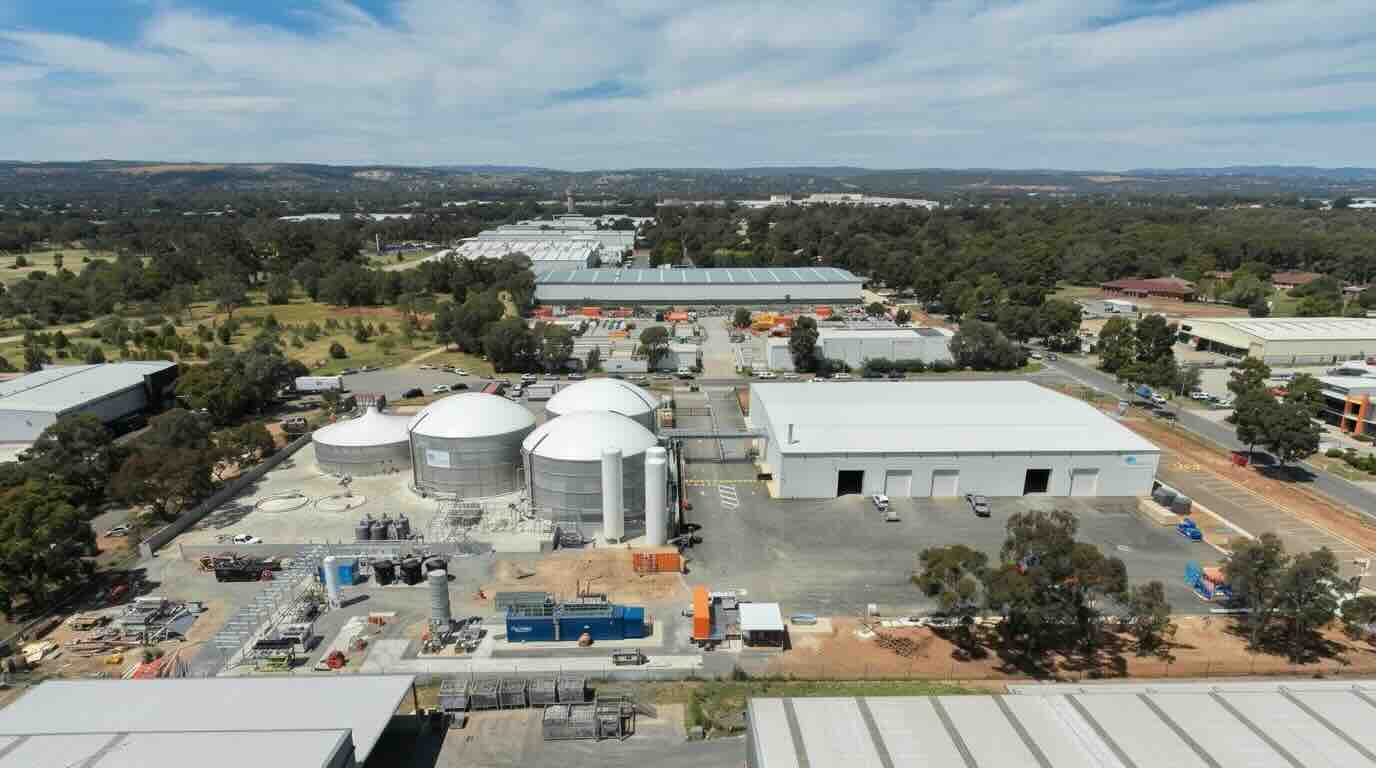
The most important development is the progress at SA1, Delorean's wholly owned Salisbury bioenergy facility in South Australia.
The operational licence issued by the South Australian Environment Protection Authority on 20 October represents a significant regulatory milestone, allowing the facility to begin accepting and processing organic waste as commissioning progresses.
Designed to process approximately 70,000 tonnes of organic waste annually, SA1 will convert material that would otherwise go to landfill into renewable natural gas, liquid carbon dioxide and other valuable by-products.
Importantly, Delorean has already established commercial relationships for its principal outputs. Origin Energy has agreed to purchase up to 200 terajoules of biomethane annually under an eight-year take-or-pay agreement, while Supagas has a 10-year agreement covering liquid carbon dioxide.
Together, these arrangements represent up to $55 million in contracted revenue opportunities over the facility's initial 10-year commercial period.
This provides an important commercial foundation as Delorean approaches commissioning. Rather than developing production capacity and subsequently searching for customers, the company has secured established offtake relationships ahead of commercial operations.
SA1 is designed to produce approximately 210 terajoules of biomethane annually, with first gas targeted during FY2027. Installation of the biomethane upgrading equipment has been completed, while work on the liquid carbon dioxide equipment continues.
The next challenge is to demonstrate consistent production, secure sufficient feedstock and convert the facility's capacity into reliable operating revenue.
NSW1 could establish a second infrastructure earnings stream
Delorean's next major opportunity is the $62.1 million NSW1 Horsley Park facility, which is designed to supply renewable gas directly to Brickworks' manufacturing operations.
The facility is expected to process 120,000 tonnes of organic waste annually and produce approximately 253 terajoules of biomethane, helping Brickworks reduce its reliance on conventional natural gas.
The funding structure is progressing. Delorean has secured $30.5 million in government grants and entered into a non-binding $20 million financing agreement with Westpac in October.
Financial close is targeted for 18 November 2026, with construction expected to commence in December, subject to completion of financing arrangements.
The remaining estimated funding requirement is approximately $11.6 million, which management intends to address through working capital, research and development tax refunds, equity and additional debt.
NSW1 also benefits from a 25-year lease and biomethane offtake arrangement with Brickworks. The estimated construction and commissioning period is approximately 21 months, with initial waste acceptance and first gas anticipated during 2028.
Successful delivery would give Delorean a second substantial infrastructure asset and strengthen its recurring revenue base.
Financial results show progress, but liquidity remains important
Delorean's FY2026 results demonstrate a business undergoing considerable change.
Revenue was $9.34 million, compared with $19.52 million in FY2025, reflecting the substantial completion of the $53 million Yarra Valley Water Lilydale construction contract.
However, EBITDA improved to $985,000 from a loss of $6.61 million, while the net loss narrowed to approximately $115,000 from $8.98 million. Gross profit also improved to $691,000 from a loss of $3.30 million.
These are encouraging developments, although the reported earnings need to be considered alongside other income and government incentives when assessing their sustainability.
Lilydale has transitioned into its operations and maintenance phase, supported by a contract worth approximately $10 million over its initial three-year term.
The longer-term opportunity is to reduce dependence on large, project-based construction revenue and establish a more predictable earnings base through waste processing, renewable gas sales and associated products.
Funding remains an important consideration. At 30 September 2026, Delorean reported $2.48 million in cash and cash equivalents, including $1.59 million held as security for bank guarantees. This leaves approximately $893,000 in unrestricted bank balances.
Operating cash outflow was $2.52 million during the September quarter, while infrastructure capital expenditure reached $4.31 million.
The company reported 2.52 quarters of estimated funding availability under its Appendix 4C calculation, incorporating available cash and undrawn financing facilities. It also had $47.64 million in drawn financing facilities and $3.87 million undrawn.
One important near-term consideration is the $12.12 million NAB borrowing facility scheduled to mature on 17 December 2026. Refinancing and liquidity management will therefore remain important as the company advances its development programme.
A growing pipeline offers further expansion opportunities
Beyond Salisbury and Horsley Park, Delorean is progressing opportunities in Victoria and Queensland.
Its work with Opal at the Maryvale paper mill is particularly interesting. The completed concept stage of a feasibility study identified the potential to convert organic residues and paper manufacturing by-products into renewable gas.
The broader near-term development pipeline exceeds $200 million, providing opportunities to replicate the company's infrastructure model across industrial and waste markets.
These projects remain at different stages of development, but successful delivery of SA1 and NSW1 could provide a stronger foundation for expanding the portfolio.
Insight: Delorean is approaching the point where infrastructure can generate recurring earnings
We see the opportunity in Delorean's transition from an established bioenergy engineering business into an infrastructure owner and operator. The combination of up to $55 million in SA1 contracted revenue opportunities, a $30.5 million NSW1 grant package and a development pipeline exceeding $200 million provides a meaningful foundation for expansion. Importantly, the next stage is increasingly about operational delivery rather than proving the underlying technology. SA1's production volumes, contracted deliveries and cash generation will be the key measures to watch.

 Mark Elzayed•






