Noumi Limited (ASX: NOU) faces a defining moment as its proposed acquisition by major shareholder Arrovest progresses through the scheme approval process, potentially ending the dairy and plant-based beverage producer's ASX listing.
With approximately $610 million in convertible notes maturing in May 2027, the proposed transaction offers a potential solution to financing pressures that have overshadowed improvements in the company's operating performance.
The central question is whether Noumi's established consumer brands can generate sustainable value under a more manageable capital structure.
Key Numbers
- $0.1234 per share: Cash consideration proposed under Arrovest's takeover.
- $610 million: Approximate convertible note obligations maturing in May 2027.
- $648.4 million: FY26 revenue, representing 8.8% annual growth.
- $61.8 million: FY26 adjusted operating EBITDA, up 7.6%.
- $25.3 million: Combined unrestricted cash and undrawn financing facilities at 30 September 2026.
The Latest Development
Noumi's proposed takeover reached a significant milestone on 5 November 2026, with separate scheme meetings held for shareholders and listed optionholders.
The company released its Results of Scheme Meetings announcement following the meetings, although the precise voting outcomes could not be independently verified.
Under the agreement announced on 21 July, Arrovest proposes to acquire Noumi shares it does not already own for $0.1234 each, while listed options would be cancelled for $0.002 per option.
The share consideration represented a 12.2% premium to Noumi's closing share price on 20 July 2026.
An important clarification emerged on 29 October when Noumi disclosed that Arrovest intended to transfer some existing shares to fellow group member Greencore Development.
The arrangement would allow Noumi to remain within a tax consolidated group. Consequently, Noumi would become an Arrovest subsidiary rather than a wholly owned subsidiary of Arrovest itself.
The Independent Board Committee considered this change immaterial to the transaction's economic outcome for securityholders.
What Stands Out to Us
Noumi's financial performance highlights the difference between operating recovery and balance-sheet strength.
FY26 revenue increased 8.8% to $648.4 million, while adjusted operating EBITDA rose to $61.8 million.
However, the company recorded a statutory net loss attributable to shareholders of $67.2 million.
September quarter revenue declined 1.4% to $160.2 million, reflecting weaker Dairy and Nutritionals sales.
Plant-based Milks provided a positive counterweight, with revenue increasing 10.7% to $52.1 million.
Operating cash inflow reached $7.9 million, although unrestricted cash remained at just $15.3 million.
The contrast is substantial. Noumi generates meaningful operating earnings but faces debt obligations far beyond its immediately available liquidity.
This complicates conventional equity valuation. Any assessment using EBITDA multiples must account for convertible notes, other borrowings and the claims of creditors before determining the residual value attributable to shareholders.
What the Company Is Doing Now
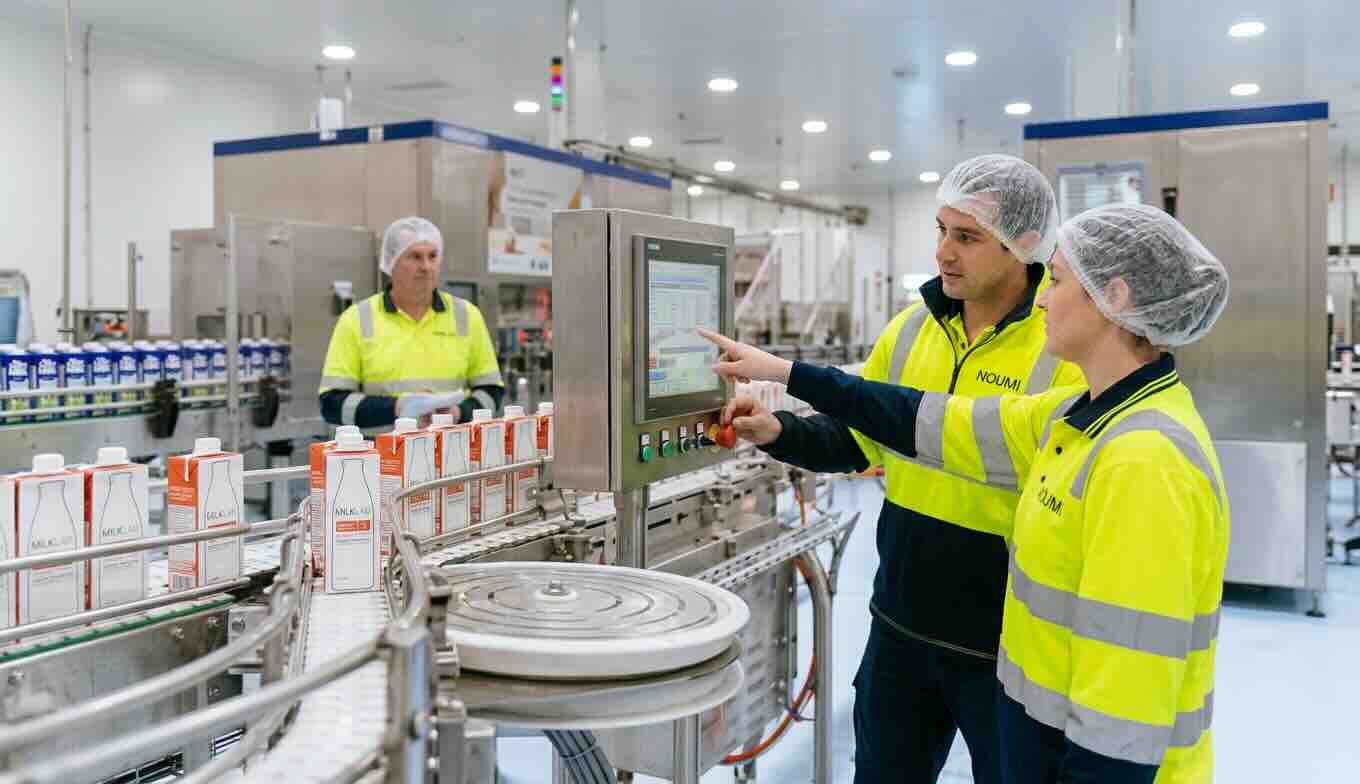
Noumi continues expanding its Milklab brand across domestic and international markets while managing weaker performance elsewhere in its portfolio.
Milklab revenue increased 7.6% to $43.9 million during the September quarter, including $7 million in export sales.
However, management identified shipment timing as a contributor to quarterly growth, limiting conclusions about the underlying demand trend.
Meanwhile, Arrovest has strengthened its position through acquisitions of outstanding convertible notes, supporting its proposed coordinated debt and equity restructuring.
Insight: Can Noumi's Brands Outgrow Its Financial Constraints?
We think Noumi's operating business has greater commercial strength than its capital structure suggests. Milklab's established distribution, export exposure and continuing revenue growth provide evidence of brand value. However, the substantial convertible note maturity makes an independent refinancing outcome difficult to assess confidently. The proposed Arrovest transaction offers a potential resolution, but it should not be mistaken for proof that the operating business has overcome its financial challenges. Sustainable cash generation, lower financing costs and improved profitability remain the critical measures of underlying business quality.
What Happens Next?
The immediate focus shifts to the confirmed scheme voting outcomes, outstanding transaction conditions and the second court hearing scheduled for 10 November 2026.
Subject to the required approvals, implementation remains targeted for 27 November 2026, followed by Noumi's removal from the ASX.
Beyond the transaction, the more consequential commercial issue remains the May 2027 debt maturity.
Noumi's operating recovery has demonstrated that its consumer brands retain commercial value. Whether that value can translate into sustainable profitability will depend heavily on the company's future financing structure and cash-generating capacity.


 Mark Elzayed•





