Terra Metals Limited (ASX: TM1) is advancing one of its most important exploration milestones at the Dante Project in Western Australia, but a newly detailed tenure dispute has introduced another consideration for shareholders.
The company holds $57.9 million in cash and has completed approximately 76,000 metres of drilling at its Southwest platinum group metals, copper and nickel discovery. However, its latest tenure disclosure highlights an existing royalty arrangement and a disputed caveat over a key exploration licence.
The central question is whether Terra can convert its expanding mineral discovery into a commercially viable project without ownership-related complications or escalating development costs.
Key Numbers
- $57.9 million: Cash reserves at 30 September 2026, down from $75.1 million at 30 June.
- 76,000 metres: Approximately the total drilling completed at Southwest during 2026.
- 1,350 metres: Interpreted mineralised strike length at Southwest, extending approximately 700 metres across strike.
- $17.1 million: Net operating cash outflow during the September 2026 quarter.
- 1% royalty: Existing net smelter return royalty applying to future commercial mineral production from exploration licence E69/3401.
The Latest Development: A Tenure Dispute Adds Another Consideration
Terra's latest tenure disclosure, dated 9 November 2026, provides further details concerning exploration licence E69/3401, which hosts the Southwest discovery and part of the existing Dante Basal Reefs Mineral Resources.
Under a 2018 agreement, GIB Mining Limited holds a 1% net smelter return royalty over commercial mineral production from the licence.
GIB has also asserted additional rights and lodged a caveat over the licence in February 2026.
Terra disputes those additional claims and GIB's entitlement to maintain the caveat.
Importantly, Terra maintains that the caveat does not affect its subsidiary's title to the licence or current exploration activities. No mining has commenced, meaning no royalty payments are presently due.
However, the caveat could restrict registration of future dealings involving the licence while it remains in place.
What Stands Out to Us: Strong Geology, but Commercial Questions Remain
The tenure clarification does not negate Southwest's geological potential.
October drilling delivered substantial mineralised intercepts, including 194 metres grading 1.01 grams per tonne of combined platinum, palladium and gold.
Southwest remains open along strike and at depth, providing further exploration opportunities.
Yet Terra's expenditure is significant.
September-quarter exploration and evaluation payments reached approximately $16.8 million, contributing to a $17.1 million operating cash outflow.
At that historical spending rate, the September cash balance represented approximately 3.4 quarters of funding.
Terra's shares closed at $0.145 on 9 November 2026, illustrating the market valuation context as the company approaches resource definition.
Without a maiden Southwest resource, demonstrated recoveries or established project economics, a reliable project-based valuation remains difficult.
What the Company Is Doing Now
Terra continues concentrating its operations on the 100%-owned Dante Project, with Southwest its primary exploration focus.
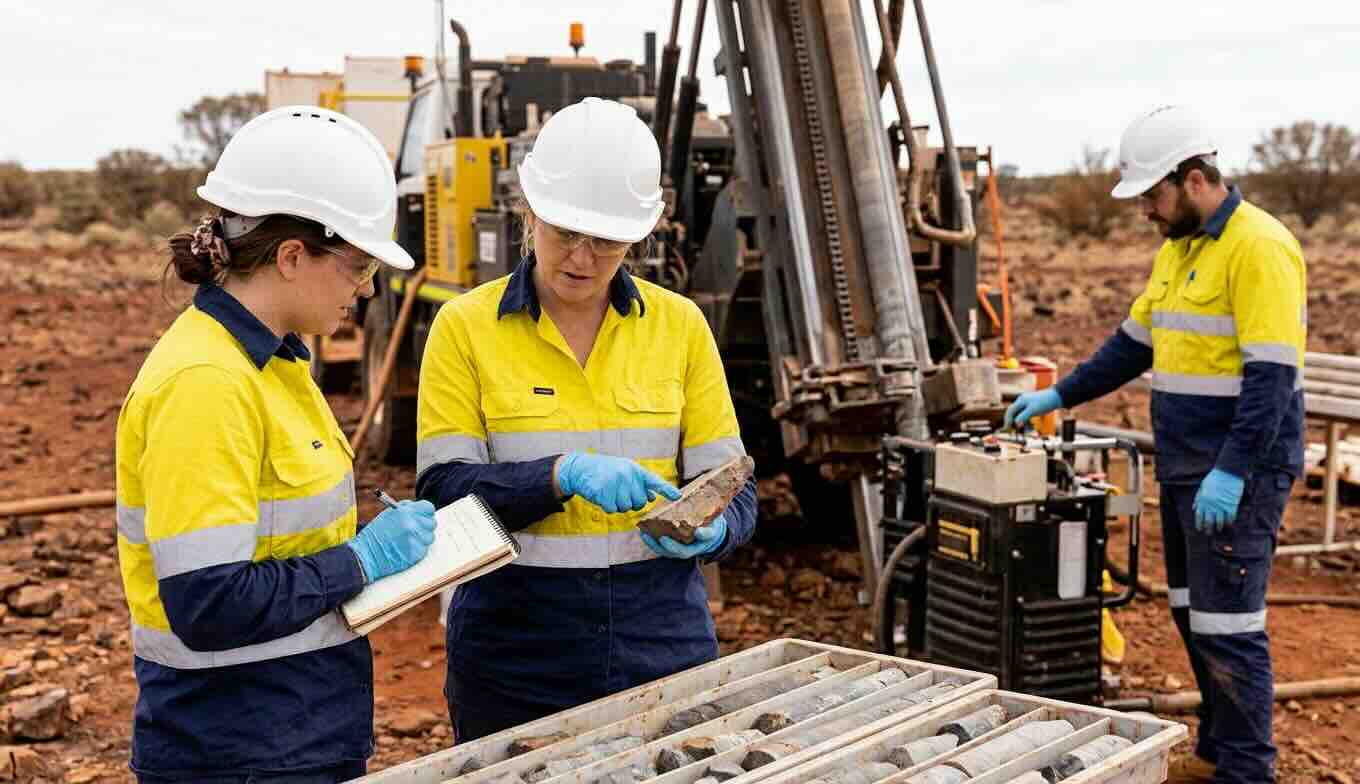
Four drilling rigs are reported on site, while more than 40,000 samples were awaiting assay results at the September quarter-end.
The company is also progressing metallurgical testing, with initial results targeted for the December 2026 quarter.
Southwest is separate from Dante's existing 148-million-tonne Basal Reefs Mineral Resource.
A successful maiden resource could expand Terra's measurable mineral inventory, although future mining economics remain unproven.
Insight: Could Funding and Tenure Risks Overshadow the Discovery?
We think Terra's combination of extensive mineralisation and substantial cash reserves provides a credible foundation for further resource growth. The latest tenure disclosure does not appear to threaten current exploration, but unresolved claims could complicate future transactions or project financing. More importantly, Southwest still lacks the technical evidence needed to establish commercial value. The 1% royalty also represents a potential future economic burden. Our assessment would strengthen with favourable metallurgy, a substantial higher-grade resource and greater clarity over tenure arrangements. Until then, exploration success remains distinct from financial viability.
What Happens Next?
Terra's next major milestones are additional assay results, initial metallurgical findings and the maiden Southwest Mineral Resource Estimate targeted for the first quarter of 2027.
A Scoping Study is planned for mid-2027, followed by a Pre-Feasibility Study.
These developments should provide more meaningful evidence about recoverable metal, potential mining costs and future capital requirements.
The company must also manage its cash expenditure and resolve outstanding tenure questions as development planning advances.
For Terra Metals, the opportunity is increasingly clear from a geological perspective. The next challenge is demonstrating whether Southwest can support an economically attractive mining project while protecting shareholder value.
 Alison Elzayed•