Delorean Corporation Limited (ASX: DEL) has reached financial close on its $62.1 million Horsley Park bioenergy facility, marking a significant milestone in its expansion into renewable gas infrastructure.
The 9 November 2026 announcement advances a major project supported by government grants, bank financing and a 25-year supply agreement with Brickworks.
With another facility approaching commissioning in South Australia, Delorean is moving closer to establishing recurring infrastructure revenue. The opportunity now centres on how effectively the company can convert its expanding project portfolio into sustainable earnings and cash flow.
Key numbers behind Delorean's growth
- $62.1 million: Total development cost of the NSW1 Horsley Park bioenergy facility.
- $30.5 million: Government grants supporting NSW1 development.
- $20 million: Executed Westpac trade finance facility supporting equipment procurement.
- 253,000 gigajoules: Estimated annual renewable gas production capacity at NSW1.
- $55 million: Potential contracted revenue associated with the SA1 Salisbury project's gas and carbon dioxide offtake arrangements.
A major project moves closer to construction
The NSW1 financial close represents an important step in Delorean's transition towards owning and operating renewable energy infrastructure.
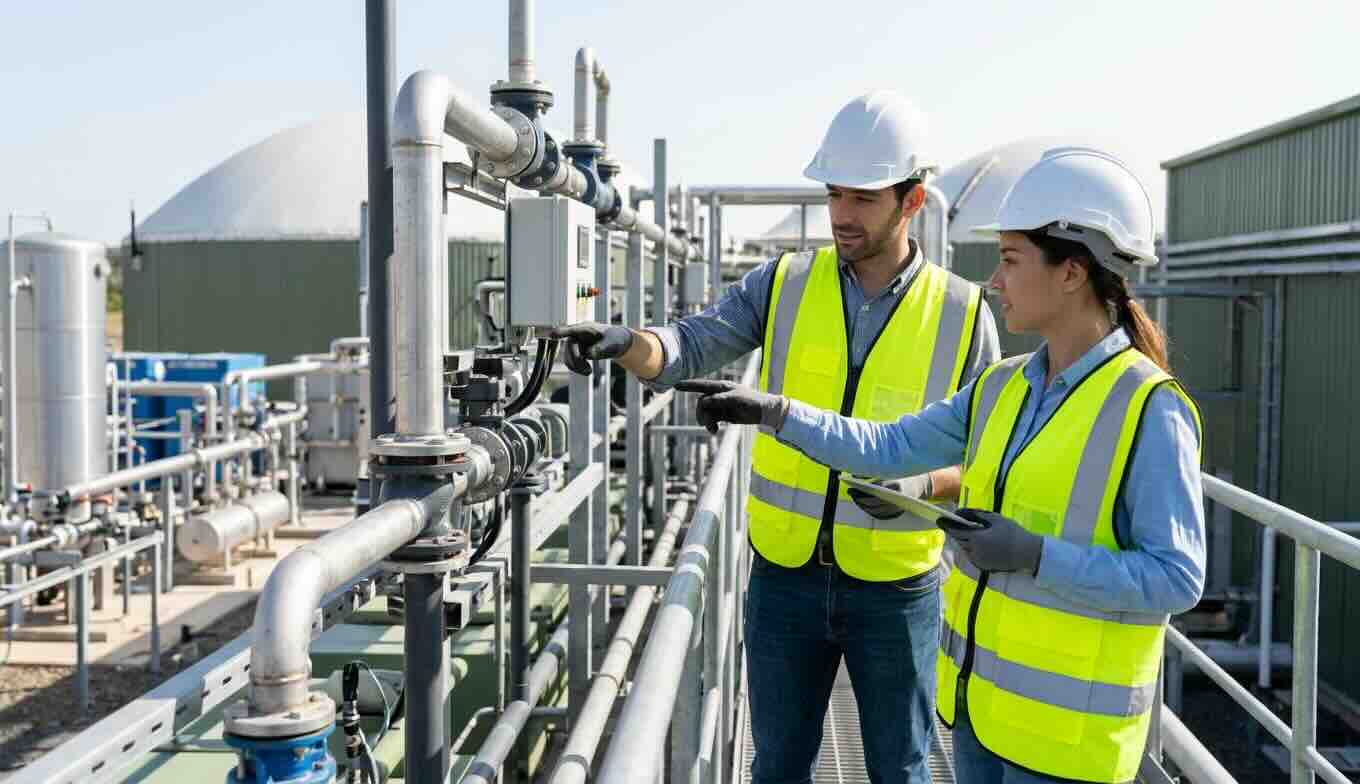
The Horsley Park facility will convert organic waste into renewable biomethane for Brickworks' manufacturing operations in western Sydney.
Designed to process approximately 120,000 tonnes of organic waste annually, the facility has approval for up to 150,000 tonnes.
Its projected renewable gas output could replace approximately 50% of the adjacent brick plant's natural gas consumption and reduce direct emissions by around 38%.
The project benefits from a 25-year land lease and binding renewable gas supply agreement with Brickworks, providing long-term demand visibility.
For Delorean, this combination of contracted demand and infrastructure ownership offers a pathway towards more predictable revenue.
Procurement is scheduled to begin in November 2026, with construction targeted for the first quarter of 2027.
Funding strengthens Delorean's development position
The NSW1 funding package combines $20 million from the NSW Government, $10.5 million from the Australian Renewable Energy Agency and a $20 million Westpac trade finance facility.
Additional funding is expected through Tanarra financing, research and development tax refunds and company cash.
Delorean has also secured commitments for a $1.4 million equity placement, with approximately $1.3 million allocated to NSW1.
These arrangements strengthen its ability to progress construction without relying entirely on corporate cash reserves.
However, Tanarra's proposed financing facility of up to $10 million remains subject to final documentation.
The proposed borrowing terms include cash interest of BBSY plus 8% and additional capitalising interest, making disciplined project execution important.
While financing costs remain a consideration, securing substantial grant support reduces the amount of commercial capital required.
Salisbury could unlock recurring earnings
Delorean's SA1 Salisbury facility in South Australia provides another potentially significant catalyst.
Construction was approximately 90% complete by September 2026, while the facility received its operational licence in October.
First waste acceptance, biomethane production and gas network injection are targeted during FY2027.
SA1 benefits from an eight-year biomethane agreement with Origin Energy covering up to 200 terajoules annually and a ten-year carbon dioxide offtake arrangement with Supagas.
Together, the arrangements represent up to $55 million in potential contracted revenue over their respective periods.
Successful commissioning would represent an important transition from infrastructure development to commercial energy production.
Financial improvement supports the longer-term strategy
Delorean's FY2026 revenue declined 52% to $9.34 million from $19.52 million in FY2025, reflecting reduced construction activity as major engineering contracts were completed.
Despite lower revenue, EBITDA improved to approximately $985,000 from a $6.61 million loss, while the net loss narrowed to $115,000.
Although $5.4 million in other income supported the result, the improvement demonstrates a stronger reported earnings position.
Operating cash outflows of $2.52 million during the September quarter highlight the importance of bringing revenue-producing infrastructure online.
The company's $2.48 million cash balance at 30 September 2026 also reinforces the value of its subsequent financing arrangements.
As operating facilities begin generating revenue, project-level cash flow and debt servicing capacity should become increasingly meaningful measures of business performance.
Insight: Could Delorean's next growth phase transform its earnings?
What stands out to us is Delorean's progress towards establishing a portfolio of contracted renewable gas infrastructure assets. NSW1's $62.1 million development package provides a foundation for expansion, while SA1 offers a nearer-term opportunity to demonstrate recurring revenue generation. We see encouraging commercial potential in the company's long-term customer agreements and growing infrastructure footprint. Although financing costs and execution remain important considerations, successful commissioning could materially strengthen Delorean's financial profile. The next critical measure is SA1's commercial production and operating cash flow.
 Alison Elzayed•