Brightstar Resources (ASX: BTR) has reached 50% engineering, procurement and construction (EPC) earned-value completion at its Goldfields Project, keeping its planned June 2027 first gold production on track.
The Western Australian gold developer is advancing a project with an estimated $606 million net present value and nearly $1 billion in forecast pre-tax free cash flow. However, as construction progresses, the critical question is whether Brightstar can deliver the production volumes and operating margins underpinning those forecasts.
Key Numbers Behind Brightstar's Gold Ambitions
- 50%: EPC earned-value completion at the Goldfields Project as at October 2026.
- 90%: Engineering completion milestone achieved during October.
- 1.5 million tonnes: Annual processing capacity planned for the Laverton gold plant.
- $606 million: Pre-tax project net present value at an 8% discount rate, assuming a $6,000-per-ounce gold price.
- $220.1 million: Liquidity reported at 30 September 2026, comprising $58.7 million cash and $161.4 million in undrawn net bond proceeds.
Goldfields Construction Advances Towards June 2027
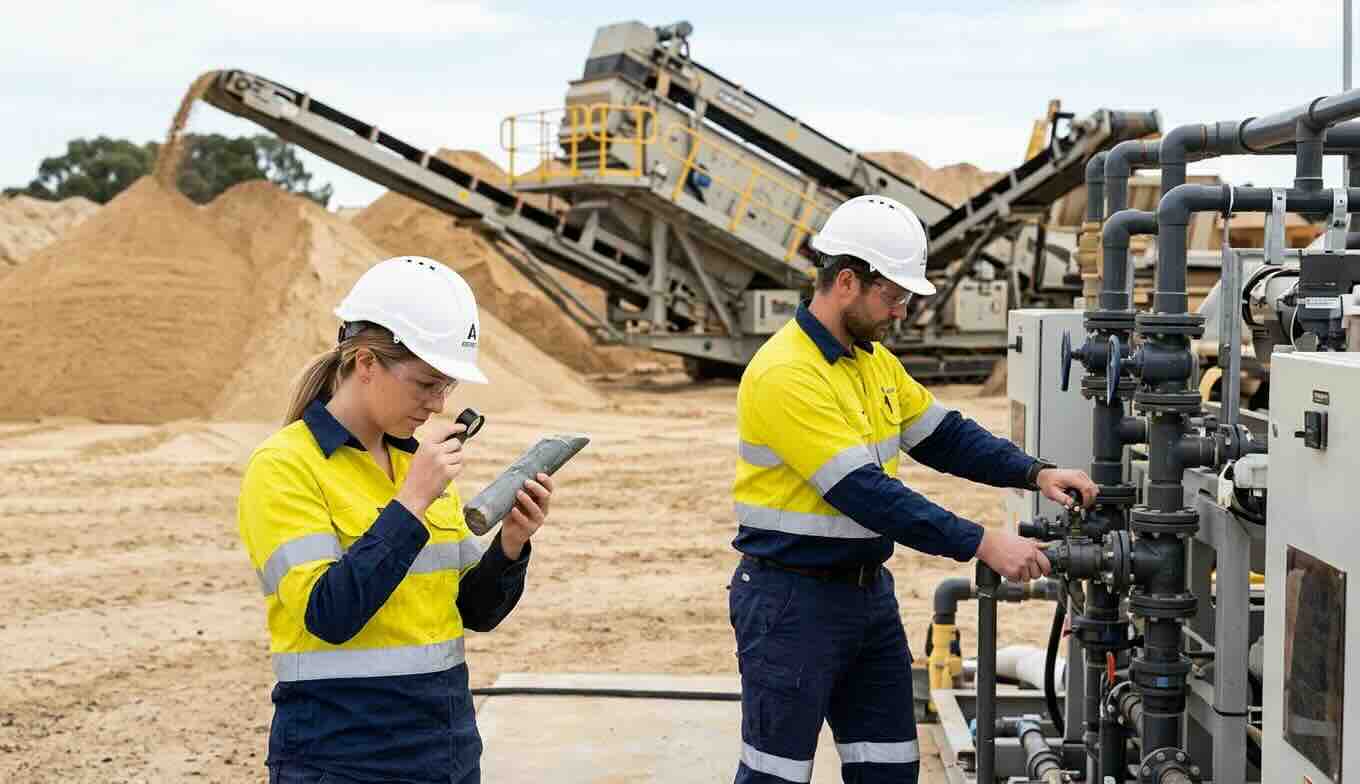
Brightstar's 10 November announcement confirmed that construction of its 100%-owned Goldfields Project remains on schedule and within its approved budget.
Major semi-autogenous grinding mill components have arrived, primary crusher concrete works are complete, and structural steel installation has commenced.
Two carbon-in-leach tanks have reached full height, while two production bores have undergone flow testing.
These developments represent measurable progress towards commissioning, although 50% EPC earned value does not necessarily mean half of all physical construction activities are complete.
Brightstar has also acquired the 223-room Boomers Mining Accommodation Camp in Laverton, providing workforce accommodation for construction, plant shutdowns and future operations.
At the Lord Byron open pit, grade-control drilling has commenced and contractor Aquirian has mobilised. The first blast is targeted for the December 2026 quarter, ahead of the previous schedule.
Open-pit mining is expected to commence early in the March 2027 quarter.
What Stands Out: Strong Economics With Significant Gold Price Exposure
Brightstar's January 2026 feasibility study outlined approximately 457,000 recovered gold ounces over an initial six-year mine life, averaging more than 75,000 ounces annually.
At an assumed gold price of $6,000 per ounce, the study forecasts $977 million in undiscounted pre-tax free cash flow, a 74% internal rate of return and all-in sustaining costs of approximately $2,998 per ounce.
However, project economics are sensitive to commodity prices.
At $5,000 per ounce, the study's pre-tax net present value declines to $301 million, compared with $606 million under the base case.
This sensitivity matters when assessing Brightstar's approximately $865 million market capitalisation reported on 10 November.
The comparison is not a direct valuation measure because market capitalisation reflects the broader portfolio, including Sandstone, while the project valuation excludes corporate-level considerations.
What Brightstar Is Doing Now
Beyond Goldfields construction, Brightstar is accelerating exploration and development studies at its Sandstone Project.
On 27 October, the company secured commitments for an $82 million placement at $0.50 per share, including a $30 million subscription from Genesis Minerals.
The placement involves issuing 164 million shares, strengthening development funding while diluting existing shareholders.
Sandstone contains approximately 3.6 million ounces of mineral resources, within Brightstar's total group resource of 5.2 million ounces.
A pre-feasibility study, including a maiden ore reserve, is targeted for the December 2026 quarter.
Insight: Can Brightstar Convert Project Value Into Sustainable Cash Flow?
We think Brightstar's most compelling feature is its combination of advanced construction, substantial mineral resources and a defined production pathway. The latest progress reduces some development uncertainty, while the strategic placement strengthens its broader growth ambitions. However, the Goldfields valuation remains highly sensitive to gold prices and successful operational execution. With forecast all-in sustaining costs approaching $3,000 per ounce, maintaining production efficiency will be essential. Our assessment is cautiously positive on development progress, but the company's ultimate financial strength remains unproven until commercial production generates sustainable cash flow.
 Alison Elzayed•