Unico Silver Limited (ASX: USL) has reported a high-grade silver intersection of 7.7 metres at 1,410 grams per tonne silver equivalent in Argentina, while identifying 55 surface exploration targets across its silver-gold projects. With $100.2 million in cash and a maiden Pre-Feasibility Study (PFS) scheduled for January 2027, the company is approaching a critical test: can its substantial resource base support a commercially viable mining operation?
Key Numbers
- 1,410g/t silver equivalent: Intersection over 7.7 metres at La Negra, including 1.2 metres at 8,835g/t.
- 55 exploration targets: Identified from 19,406 surface samples across Joaquin and Cerro Leon.
- Nine priority targets: Seven outside existing Mineral Resources and two targeting extensions.
- $100.2 million: Cash held at 30 September 2026, following a $60 million institutional placement.
- January 2027: Target release of the integrated PFS and revised Mineral Resource estimate.
High-Grade Results Strengthen the Mine Development Case
Unico's two ASX announcements on 10 November 2026 provide fresh evidence of mineralisation within existing deposits and additional exploration potential.
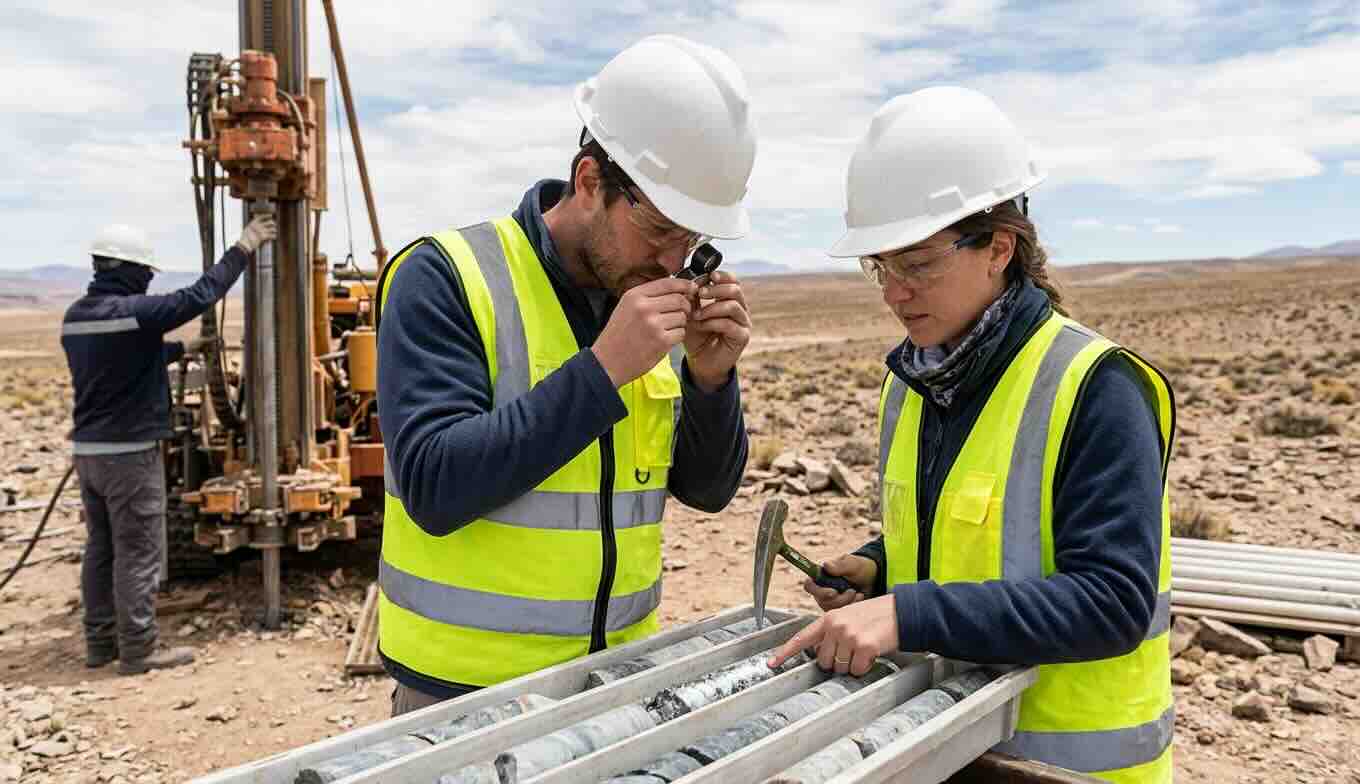
At Joaquin, hole JDD297-26 intersected 7.7 metres at 1,410g/t silver equivalent from 38 metres, including 1.2 metres at 8,835g/t.
Cerro Leon also delivered significant results, including 28 metres at 355g/t at Marta Este and 9.5 metres at 489g/t at Achen.
These results support Unico's efforts to convert Inferred Mineral Resources into higher-confidence Measured and Indicated categories.
That conversion matters because the revised resource will underpin mine planning and a maiden Ore Reserve estimate.
However, reported drilling intervals are downhole lengths, with true widths not yet established. High grades alone cannot determine mine profitability.
A New Exploration Pipeline Creates Additional Potential
Unico's second announcement identified 55 surface targets using 19,406 geochemical samples, including 5,606 collected by the company.
At La Morena, rock-chip samples returned up to 32.6g/t gold, while samples along an eastern extension returned up to 30.5g/t.
Initial drilling at La Morena intersected 36 metres at 122g/t silver equivalent, including 1.34g/t gold.
At Cerro Leon's Sierra Blanca prospect, selective rock-chip samples returned up to 2,104g/t silver.
These results suggest potential beyond existing resource boundaries.
Nevertheless, surface anomalies and selective rock-chip grades are not equivalent to drill-defined Mineral Resources. Seven priority exploration targets remain largely untested by Unico, making further drilling essential.
What Stands Out to Us
Unico's approximately 330-million-ounce silver-equivalent resource inventory provides a substantial geological foundation, while its cash reserves support continued feasibility and exploration work.
The company is fully funded for its planned PFS, regulatory application and FY27 exploration and development program.
However, funding feasibility studies is fundamentally different from financing mine construction.
Unico has not established commercial production or sustainable operating cash flow.
Without confirmed capital expenditure, recoveries, mining costs and production forecasts, a reliable project-based valuation remains premature.
What Unico Silver Is Doing Now
Unico is finalising process designs covering tank-leach and heap-leach processing alternatives, alongside mine layouts and capital cost estimates.
Environmental baseline studies are complete, with an Environmental Impact Report targeted for January 2027.
The company is also preparing an application under Argentina's Large Investment Incentive Regime, with potential inclusion targeted for the second half of 2027.
Meanwhile, the 2026–27 exploration program includes additional sampling, geological mapping and drilling, initially targeting La Morena and J26.
These initiatives could strengthen development options, although regulatory approval and exploration success remain uncertain.
Insight: Can Unico Convert Geological Scale Into Economic Value?
We think Unico's strongest advantage is the combination of substantial mineral resources, encouraging near-surface drilling and a funded development program. The 55 exploration targets provide longer-term potential, but expanding the resource is not necessarily the company's most urgent commercial priority. Establishing competitive production costs and manageable construction expenditure matters more. Its $100.2 million cash position reduces immediate financing pressure, yet construction funding remains unresolved. A PFS demonstrating robust recoveries, an economically attractive Ore Reserve and credible project economics would materially strengthen our assessment.
 Alison Elzayed•