Wagners Holding Company Limited (ASX: WGN) is building on a strong FY26 performance, targeting up to $76 million in FY27 operating earnings while pursuing a potential US$55 million LNG supply agreement in Papua New Guinea. With expanding construction materials operations, growing international demand for composite fibre products and a strengthened balance sheet, the Queensland-based group is positioning itself for its next phase of growth.
The key opportunity lies in converting this expanding project pipeline into sustainable profitability and stronger cash generation.
Key Numbers Behind Wagners' Growth Outlook
- $72 million to $76 million: FY27 earnings before interest and tax (EBIT) guidance, approximately 7% to 13% above FY26 operating EBIT.
- $40 million to $42 million: Forecast EBIT for the first half of FY27.
- US$50 million to US$55 million: Potential Papua New Guinea LNG supply agreement spanning approximately 2.5 years.
- $503.9 million: FY26 revenue, representing 16.8% annual growth.
- $63.1 million: FY26 operating cash flow, supporting an improved financial position.
Major LNG Opportunity Opens International Growth Path
Wagners' 12 November 2026 trading update highlighted a significant international opportunity following receipt of a letter of intent from the JGC-Hyundai joint venture.
The proposed agreement involves supplying aggregates and concrete for an LNG development in Papua New Guinea, potentially strengthening the company's international Project Services portfolio.
Subject to a final investment decision expected in mid-December 2026, mobilisation could commence in early 2027.
Aggregate deliveries are expected to begin in April 2027, followed by concrete supply in mid-2028.
The proposed agreement remains conditional rather than secured revenue. Nevertheless, its potential scale demonstrates Wagners' ability to compete for major infrastructure projects requiring specialised materials and delivery capabilities.
Stronger Earnings Highlight Operational Momentum
Wagners enters FY27 following a period of improving financial performance.
FY26 operating EBIT increased approximately 61% to $67.2 million, while net profit after tax rose 78.5% to $40.6 million.
Construction Materials revenue increased 28% to approximately $328 million, supported by infrastructure activity and construction demand.
Meanwhile, Composite Fibre Technologies revenue grew 36% to $93.4 million, highlighting the expanding commercial contribution of Wagners' engineered products.
Operating cash flow reached $63.1 million, although property, plant and equipment expenditure of $51.2 million reflects the capital required to support expansion.
Management has also flagged potential second-half earnings pressures from clinker prices, shipping costs and seasonal demand. These remain important considerations, but the FY27 guidance indicates expectations for continued annual earnings growth.
What Wagners Is Doing Now
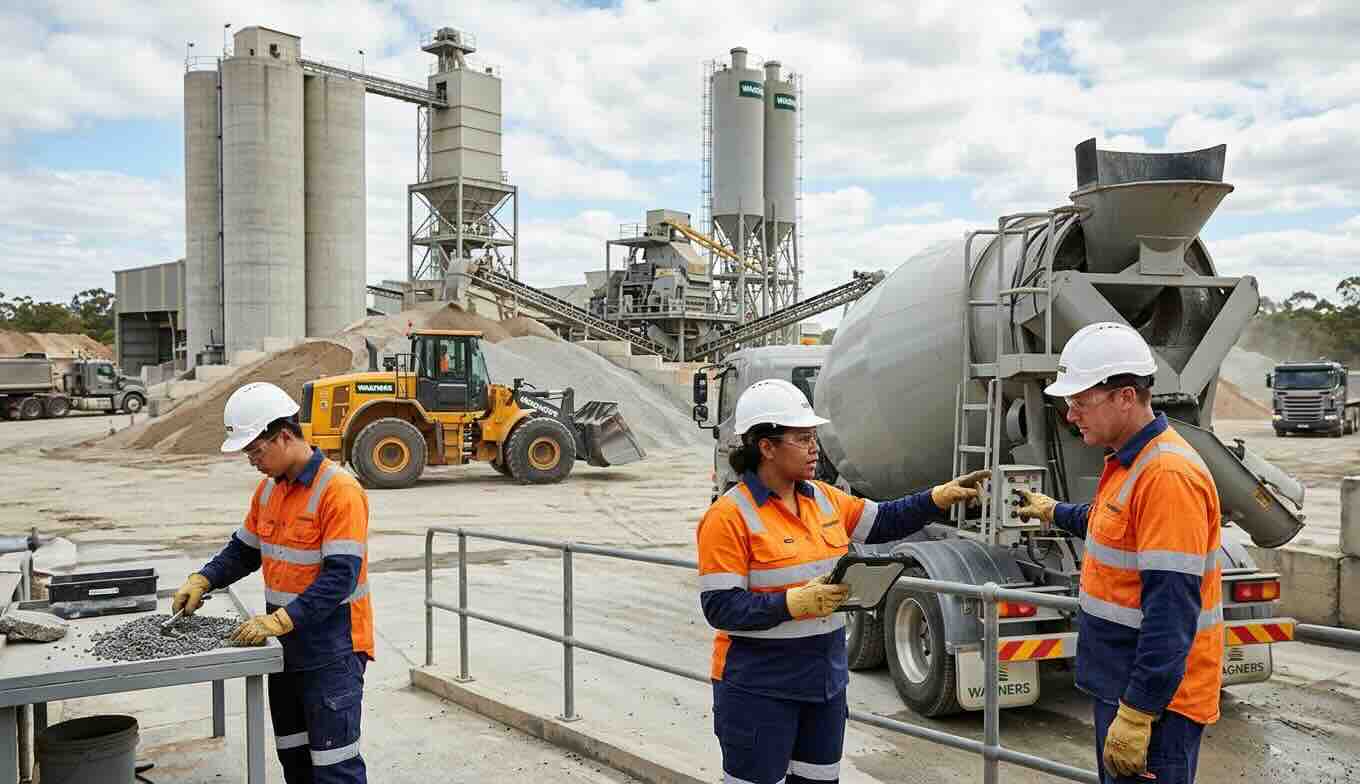
Wagners continues expanding its construction materials network across South-East Queensland.
Its Caboolture concrete plant is approaching commissioning, while three additional locations are progressing through planning and approvals.
These investments could strengthen production capacity, distribution reach and customer access across growing construction markets.
Internationally, Composite Fibre Technologies is expanding its presence.
The division has dispatched utility poles to Northern Ireland and secured a shortlist position for a potential long-term supply arrangement in the Republic of Ireland.
Its United States operations also delivered substantial revenue growth during FY26, achieving positive annual operating EBIT.
Together, these initiatives support greater geographic diversification and the potential for additional recurring product demand.
Insight: Can Wagners Turn Expansion Into Sustained Earnings Growth?
We believe Wagners is developing an increasingly attractive growth profile, supported by stronger operating earnings, diversified revenue streams and a substantially improved balance sheet. Its vertically integrated construction materials business provides an established earnings foundation, while Composite Fibre Technologies offers differentiated international growth potential. The proposed PNG agreement could further strengthen its project pipeline. Although capital expenditure and operating costs require careful management, continued earnings improvement and stronger free cash flow would reinforce the company's commercial outlook and support confidence in its longer-term growth strategy.
What Happens Next?
The most immediate catalyst is the anticipated mid-December 2026 final investment decision on the PNG LNG development.
A favourable outcome could advance Wagners towards a significant international supply contract, potentially adding to revenue visibility over the following years.
The company's first-half FY27 results will also provide an important measure of progress towards its $40 million to $42 million EBIT forecast.
Beyond these milestones, commissioning new facilities, expanding composite fibre sales and maintaining operating margins will be central to future performance.
With an expanding operational footprint, improving earnings and several commercial opportunities progressing, Wagners enters FY27 with encouraging momentum and a clearer pathway towards building a larger, more diversified business.

 Mark Elzayed•