STOCKSCOPE

Imricor Medical Systems (ASX: IMR) Sees US Revenue Surge 437% as Hospital Expansion Opens New Growth Opportunities

Danny Aad

Danny Aad

Technology & Biotechnology Specialist | StockScope

Published:13 Nov 2026
Imricor Medical Systems (ASX: IMR) Sees US Revenue Surge 437% as Hospital Expansion Opens New Growth Opportunities

Imricor Medical Systems (ASX: IMR) is gaining commercial momentum in the United States, with September-quarter revenue climbing 437% as its innovative cardiac technology begins generating sales in the world's largest healthcare market.

With US$62.1 million in cash, its first American hospital customers and further regulatory milestones approaching, Imricor is building the foundations for broader commercial adoption. The next opportunity lies in converting these early achievements into sustained revenue growth.

Key Numbers

  • US$188,000: September-quarter revenue, up 437% from US$34,791 a year earlier.
  • US$62.1 million: Cash and cash equivalents at 30 September 2026.
  • US$41.6 million: Net proceeds from the May 2026 equity capital raising.
  • US$21.4 million: Operating cash outflow for the first nine months of 2026.
  • US$212,452: Nine-month revenue, reflecting the early stage of commercial expansion.

First US Sales Mark an Important Commercial Milestone

Imricor's September-quarter results highlight meaningful progress in its transition from medical technology development to commercial deployment.

The company recorded its first US commercial revenue following the sale of a NorthStar Mapping System in September.

This follows commercial relationships with Rady Children's Hospital in San Diego and Children's Medical Center Dallas, establishing an initial foothold in the American healthcare market.

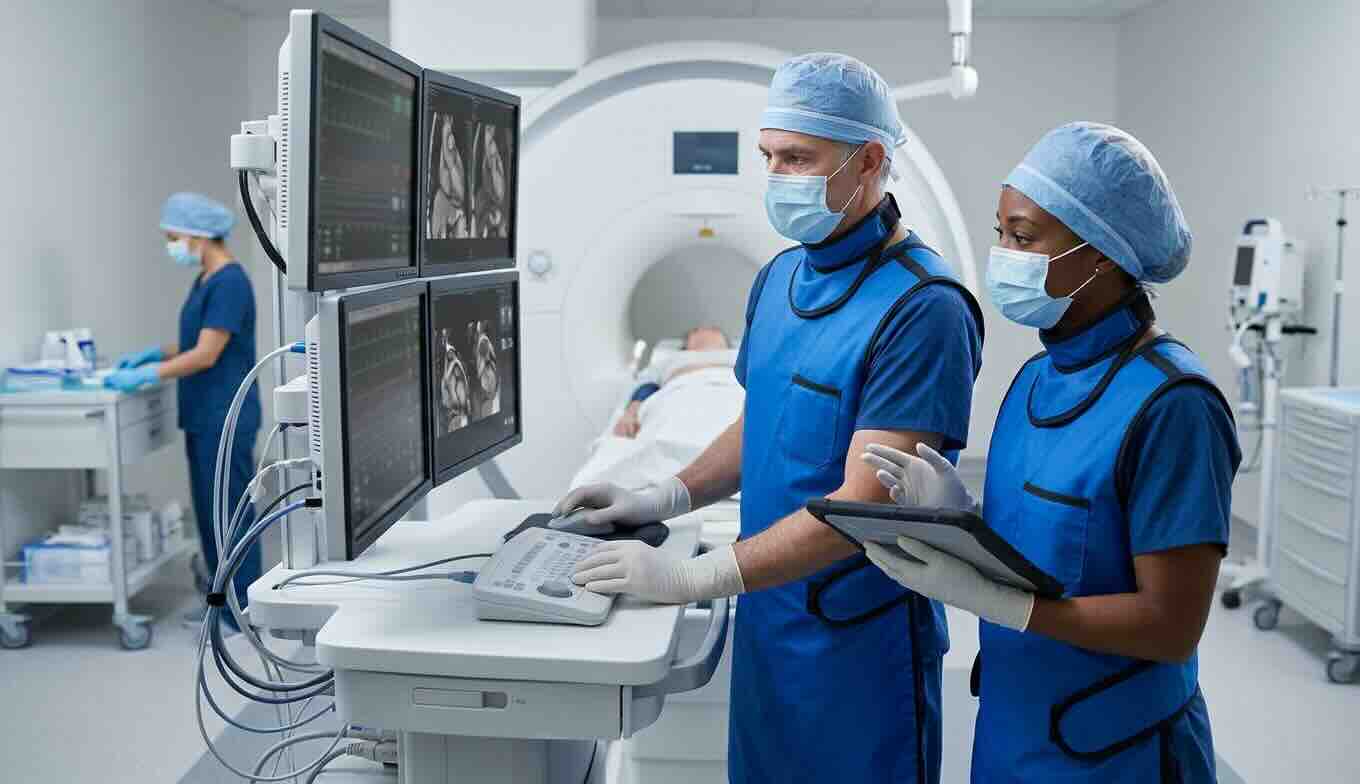
NorthStar enables cardiac procedures using magnetic resonance imaging rather than conventional X-ray guidance, potentially reducing radiation exposure while providing detailed anatomical visualisation.

For Imricor, these early hospital relationships represent more than individual equipment sales. They provide opportunities to demonstrate clinical performance, establish reference sites and support future adoption.

Although nine-month revenue declined approximately 8% to US$212,452, the substantial September-quarter increase suggests commercial activity is beginning to accelerate.

What Stands Out to Us

Imricor's competitive opportunity centres on its specialised technology, regulatory progress and collaboration with established medical imaging providers.

Its relationship with Philips, including the introduction of a commercial interventional magnetic resonance laboratory solution in August, could help expand its reach into additional hospitals.

Importantly, the business model offers potential for revenue beyond initial equipment installations through recurring consumables associated with cardiac procedures.

The company's financial position also provides flexibility to pursue expansion.

Imricor held US$62.1 million in cash at September's end, following its May capital raising.

Nine-month operating cash outflow reached US$21.4 million, reflecting continued investment in research, regulatory approvals and commercial operations.

At that historical operating cash consumption rate, available cash represents approximately 26 months of theoretical operating runway, excluding future spending changes and other financial obligations.

The company also reported US$29.1 million in related-party convertible notes classified as current liabilities, making future financing arrangements an important consideration.

With revenue still emerging, valuation depends primarily on commercial adoption, future recurring sales and the company's ability to achieve operating scale.

What the Company Is Doing Now

Imricor is advancing several initiatives designed to strengthen its commercial position.

Alongside its US hospital expansion, the company continues progressing regulatory approvals for additional cardiac ablation technology.

In October, the US Food and Drug Administration completed its review of the third module of Imricor's premarket approval application.

The review identified a software-related deficiency involving the RF-5000 System, which the company indicated it had addressed through an operating system update.

Imricor is targeting submission of its fourth module in November 2026.

Further regulatory progress could expand the range of procedures supported by its technology and strengthen its commercial offering.

Insight: Is Imricor Approaching a New Phase of Commercial Growth?

We see encouraging signs that Imricor's years of technology development are beginning to translate into commercial opportunities. Its first US sales, hospital relationships and Philips collaboration provide a credible foundation for expansion. The substantial cash balance also supports continued investment as adoption develops. While operating losses and funding obligations remain important considerations, the more significant opportunity lies in establishing recurring revenue across a growing hospital network. We think sustained customer growth, regulatory progress and higher procedure volumes could materially strengthen Imricor's long-term commercial outlook.

What Happens Next?

The coming 6–18 months could be important for Imricor as it pursues additional US hospital installations, progresses regulatory submissions and works to expand recurring product sales.

Further customer wins, increasing procedure volumes and stronger quarterly revenue would provide evidence that its commercial strategy is gaining traction.

For shareholders, Imricor's growing US presence represents an encouraging development. The next milestone will be demonstrating that early hospital adoption can evolve into a scalable, recurring revenue business with a credible path towards sustainable profitability.

Danny Aad

Danny Aad

(Technology & Biotechnology Specialist | StockScope)

Danny Aad is an experienced technology executive with a distinguished career spanning more than three decades, including senior leadership positions as Chief Technology Officer (CTO) across the technology and biotechnology sectors. With extensive expertise in technology strategy, digital innovation and the evolving biotechnology landscape, Danny brings a wealth of industry knowledge and technical insight to his analysis of emerging technologies, corporate developments and investment opportunities.

DisclaimerInformation on Stockscope is general in nature and does not constitute financial product advice. It does not take into account your personal objectives, financial situation or needs. Seek independent advice from a qualified financial adviser before making an investment decision. Stockscope and its affiliates do not guarantee the accuracy or completeness of information published on this website. To the extent permitted by law, they accept no liability for any claim, loss or damage arising from its use or reliance on it. Stockscope and its associates may have commercial relationships with companies featured on this website, hold securities in those companies, or receive commissions in connection with capital raisings.

Continue Reading

ASX Sells Off as Paladin Slumps 17%: Rising Bond Yields and NVIDIA Shock Rattle Global Markets
Market Briefings
Market Briefings

ASX Sells Off as Paladin Slumps 17%: Rising Bond Yields and NVIDIA Shock Rattle Global Markets

Australian equities: what moved the ASX 200? Australian shares finished Friday, 13 November, under pressure, with the S&P/ASX 200 falling 65.4 points, or 0.71%, to close at 9,082.2. The in...

Mark ElzayedMark Elzayed•
Carma (ASX: CMA) Doubles Gross Profit as Vehicle Sales Surge, Setting the Stage for Its Next Growth Phase
Consumer
Consumer

Carma (ASX: CMA) Doubles Gross Profit as Vehicle Sales Surge, Setting the Stage for Its Next Growth Phase

Carma Limited ASX: CMA is building momentum in Australia's online used-car market, with annual gross profit more than doubling and vehicle sales surging 86%. Its 13 November 2026 annual gene...

Alison ElzayedAlison Elzayed•
Neurizon Therapeutics (ASX: NUZ) Advances ALS Treatment Towards Pivotal 2027 Results as $12 Million Funding Facility Strengthens Outlook
Biotech & Health
Biotech & Health

Neurizon Therapeutics (ASX: NUZ) Advances ALS Treatment Towards Pivotal 2027 Results as $12 Million Funding Facility Strengthens Outlook

Neurizon Therapeutics ASX: NUZ is building momentum towards a potentially transformative clinical milestone, with two developments on 13 November 2026 strengthening its position ahead of piv...

Danny AadDanny Aad•
Artrya (ASX: AYA) Secures Fifth US Hospital Deal as Commercial Momentum Builds in $580 Million Growth Story
Biotech & Health
Biotech & Health

Artrya (ASX: AYA) Secures Fifth US Hospital Deal as Commercial Momentum Builds in $580 Million Growth Story

Artrya Limited ASX: AYA is gaining momentum in the US healthcare market, securing a five-year agreement with Arizona-based HonorHealth worth at least US$500,000. The 13 November announcemen...

Danny AadDanny Aad•
Omega Oil & Gas (ASX: OMA) Hits Gas at Queensland’s Deepest Well as Taroom Trough Opportunity Grows
Energy
Energy

Omega Oil & Gas (ASX: OMA) Hits Gas at Queensland’s Deepest Well as Taroom Trough Opportunity Grows

Gas reaching the surface and the highest gas shows recorded to date have added fresh momentum to Omega Oil & Gas Limited ASX: OMA, strengthening the emerging resource story in Queensland’s T...

Alison ElzayedAlison Elzayed•
Big River Industries (ASX: BRI) Secures $156 Million Takeover Deal at 45.9% Premium as Earnings Recovery Gains Momentum
Industrials
Industrials

Big River Industries (ASX: BRI) Secures $156 Million Takeover Deal at 45.9% Premium as Earnings Recovery Gains Momentum

Big River Industries ASX: BRI has secured a $1.62-per-share cash takeover proposal, valuing the building products manufacturer and distributor at approximately $156 million. The agreement r...

Alison ElzayedAlison Elzayed•
Loading more stories...