Waratah Minerals (ASX: WTM) is entering an ambitious growth phase after securing firm commitments for a $50 million capital raising to accelerate exploration at its Spur Gold Project in New South Wales.
With a maiden 3.1 million-ounce gold resource already established and more than 100,000 metres of drilling planned, Waratah is positioning itself to pursue a substantially larger gold resource. The opportunity now lies in converting its geological success into greater project scale and long-term commercial value.
Key Numbers
- $50 million: Placement commitments secured at $0.65 per share, before costs.
- 3.1 million ounces: Maiden gold Mineral Resource grading 1.2 grams per tonne.
- 27% Indicated, 73% Inferred: Current resource classification, highlighting potential for further resource definition.
- 100,000+ metres: Planned drilling campaign targeting resource expansion and new discoveries.
- $44.5 million: Cash held at 30 September 2026, before the latest placement.
$50 Million Raising Strengthens Waratah's Growth Strategy
Waratah has secured firm commitments for approximately 76.9 million new shares at $0.65 each, providing additional financial capacity to accelerate exploration across its flagship Spur Gold Project.
The placement price represents a 5.8% discount to the company's 16 November closing price of $0.69.
The raising will occur in two tranches, with approximately 31.2 million shares issued under existing placement capacity and the remaining 45.7 million subject to shareholder approval.
Combined with its previously reported cash reserves, the funding strengthens Waratah's position to execute an extensive exploration program.
Importantly, the capital is directed towards expanding and improving resource confidence rather than immediately funding mine construction.
This distinction matters because additional drilling could establish the geological foundation for a larger development opportunity while providing information needed for future economic assessments.
What Stands Out to Us
Waratah's most compelling advantage is the scale of its existing resource relative to the broader mineralised corridor.
The maiden 3.1 million-ounce resource covers approximately two kilometres of a six-kilometre priority corridor, leaving substantial ground available for further exploration.
The company has also outlined a conceptual Exploration Target of 5.1 million to 10.4 million ounces outside the current resource.
While this target remains conceptual and cannot be treated as an established Mineral Resource, it highlights the exploration potential management intends to test.
Recent drilling has strengthened that geological proposition.
Results announced on 9 November included 7.5 metres grading 8.09 grams per tonne gold, while additional drilling identified mineralisation connecting Spur with the historic Essex mine.
These developments suggest potential continuity across a broader mineralised system.
For shareholders, successful resource expansion could improve project scale, although the economic value of additional ounces will depend on grade, mining conditions and future development costs.
What Waratah Is Doing Now
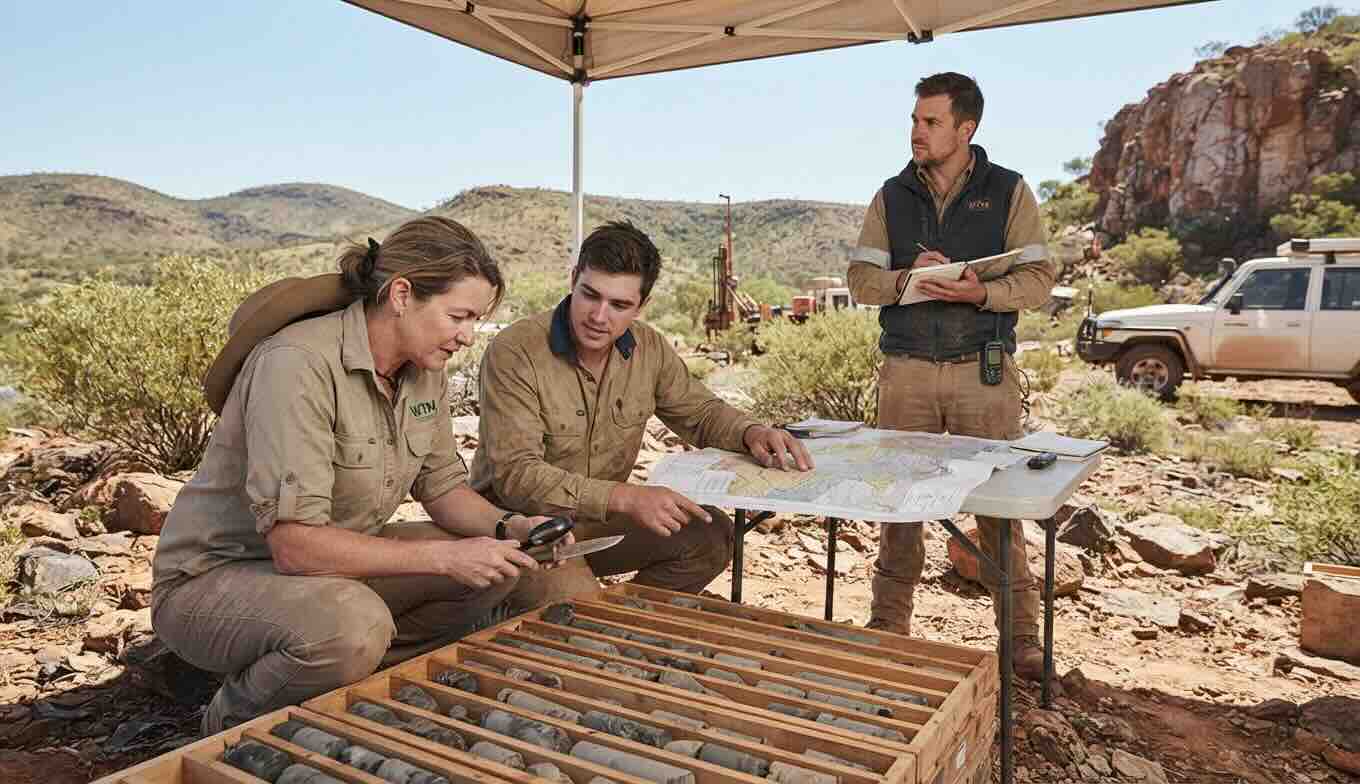
Waratah is advancing an extensive drilling campaign across Spur and Consols, supported by exploration targeting Ironclad, Goldenclad, Alpine and Gazzards.
The program includes approximately 82,000 metres of resource extension and infill drilling, alongside another 18,000 metres targeting additional mineralised zones.
The company has also strengthened its district position through the acquisition of the Ironclad Mining Lease.
Earlier metallurgical testing at Consols delivered preliminary gold recoveries of 89% to 93% using gravity and conventional leaching methods.
Although further testing is required, these results provide encouraging initial evidence for potential gold recovery using established processing techniques.
Insight: Could Spur Become a Much Larger Gold Development Opportunity?
We think Waratah has established an increasingly compelling exploration growth story, supported by a substantial maiden resource, encouraging drilling results and a strengthened funding position. The $50 million placement provides greater capacity to test the broader mineralised corridor and potentially increase resource confidence. Although issuing approximately 76.9 million shares introduces dilution, successful resource growth could help offset that impact through additional project value. The critical next step is demonstrating that expanded mineralisation can support commercially attractive development economics. Stronger resource classification, metallurgical confidence and preliminary cost estimates would further reinforce our positive assessment.
What Happens Next?
Waratah's immediate priorities include completing the placement, securing shareholder approval for the second tranche and delivering results from its expanded drilling program.
Management is targeting resource growth towards five million ounces, with an updated Mineral Resource Estimate expected in the September quarter of 2027.
The next resource update could be particularly significant if drilling increases both total contained gold and the proportion classified as Indicated.
Future economic studies will also be important in assessing potential mine development costs, processing requirements and commercial viability.
Waratah has already demonstrated meaningful geological scale at Spur. With additional funding and an extensive drilling program, the company now has an opportunity to establish whether that resource can grow into a considerably larger gold development project.
The coming exploration results will be central to determining how much of that potential can be converted into measurable long-term value.

 Mark Elzayed•






